|
시장보고서
상품코드
2124478
라틴아메리카의 데이터센터 건설 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Latin America Data Center Construction - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
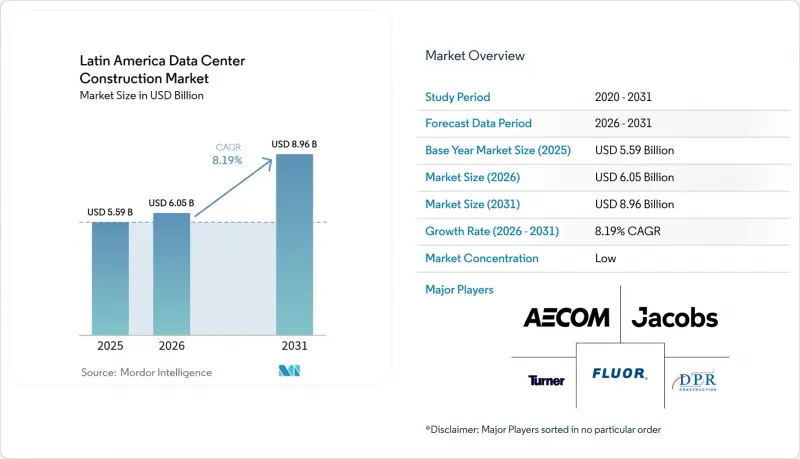
에 의하면, 라틴아메리카의 데이터센터 건설 시장 규모는 2025년 55억 9,000만 달러로 평가되었습니다. 2026년에는 60억 5,000만 달러로 확대되어 2026년부터 2031년에 걸쳐 CAGR 8.19%로 성장을 지속하여, 2031년에는 89억 6,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 인프라(전기 인프라, 기계 인프라 등), 티어 기준(Tier I·II, Tier III 등), 최종 사용자(은행 및 금융 서비스·보험, IT 및 통신 등), 데이터센터 유형(코로케이션, 하이퍼스케일 등), 지역(브라질, 멕시코 등)별로 분류되어 있습니다. 예측치는 달러 기준입니다.
라틴아메리카의 데이터센터 건설 시장 동향 및 인사이트
클라우드, AI, 빅데이터 워크로드의 가속화
현재, 인공지능(AI) 용도에는 기존 컴퓨팅의 3-5배에 달하는 전력 밀도가 요구되고 있어, 사업자들은 열 아키텍처와 전기 토폴로지를 재설계해야 하는 상황에 직면해 있습니다. 마이크로소프트의 브라질에 대한 27억 달러 투자와 스칼라(Scala)사의 500억 달러 규모의 ‘AI 시티’ 프로젝트는 새로운 요구 사항의 규모를 여실히 보여주고 있습니다. 액체 냉각 기술의 도입이 가속화되고 있으며, 현지에서 제조된 Delta Cube 시스템을 통해 ODATA 사이트의 에너지 소비가 절감되고 있습니다. 지역 정책 입안자들은 AI 인프라를 디지털 경쟁력의 핵심으로 삼고, 허가 절차의 신속화 및 대상에 맞춘 세제 혜택을 추진하고 있습니다. 시공업체들은 고밀도 MEP 패키지 입찰이 급증하고 있다고 보고하고 있으며, 버스웨이, 펌프, 판형 열교환기 공급업체들은 해당 지역 내 생산 거점을 확대되고 있습니다.
미국 주요 클라우드 기업들의 하이퍼스케일 캠퍼스 건설
Amazon Web Services, Microsoft Azure, Google Cloud 등 3사는 2030년까지 라틴아메리카에 총 100억 달러 이상을 투자할 예정입니다. 상파울루, 케레타로, 보고타에 건설될 수 기가와트 규모의 캠퍼스에는 이중화된 400kV 전력 공급, 첨단 소화 설비, 그리고 시운전 기간을 12-18개월로 단축하는 조립식 전원실이 필요합니다. 지역 광섬유 업계의 선두주자인 V.tal사만 해도, 브라질에서 하이퍼스케일 대응 셸 시설을 제공하기 위해 10억 달러의 예산을 편성했습니다. 이러한 ‘빌드 투 슈트(Build-to-Suit)’ 모델은 통합형 설계 및 시공에 정통한 EPC 기업에 유리하게 작용하며, 주요 도시의 전력 공급이逼迫함에 따라 수요는 2선 도시로 확산되고 있습니다.
송전망의 병목 현상과 전기요금의 급등
멕시코에서는 전력 회사와의 계통 연계 대기 기간이 18개월에 달하는 문제에 직면해 있어, 개발업체들은 디젤 발전 설비를 조달할 수밖에 없는 상황입니다. 이로 인해 프로젝트의 설비 투자(CAPEX)가 최대 25% 증가하고, 운영비도 늘어나고 있습니다. 아르헨티나에서는 거시경제의 변동이 요금 리스크를 증폭시키고 있는 반면, 상파울루의 국지적인 송전망 혼잡으로 인해 개발업자들은 캄피나스나 포르투알레그레로 진출할 수밖에 없는 실정입니다. AI 워크로드로 인해 전력 밀도가 두 배로 증가하면서, 원래 상업용 사무실 부하를 가정하고 설계된 송전망에 부담이 가중되고 있습니다. 사업자들은 예측 가능한 가격을 확보하기 위해 15년 기간의 재생에너지 전력 구매 계약(PPA)을 체결하는 사례가 증가하고 있지만, 중소규모 기업들은 이러한 계약을 체결할 재정적 기반이 부족하여 중견 시장 부문에서의 도입이 주춤하고 있습니다.
부문별 분석
2025년 라틴아메리카의 데이터센터 건설 시장 규모 중 기계 인프라가 37.35%를 차지했습니다. 이는 브라질, 페루, 콜롬비아 전역에 걸친 고온 다습한 기후 조건으로 인해 견고한 냉수 루프, 증발 냉각, 맞춤형 격리 시스템이 필요하기 때문입니다. 전기 인프라 내의 배전반, 개폐 장치 및 UPS 어레이는 은행업 및 통신업에서 가동 시간 확보 요건을 충족하는 데 여전히 필수적입니다. 일반 건설 분야에서는 미션 크리티컬 시설을 보호하기 위한 내진 보강 및 허리케인 대응 외장 등, 견고한 셸 앤 코어(골조 및 핵심 구조)에 대한 투자가 주를 이루고 있습니다.
IT 인프라는 AI 추론에 최적화된 서버, NVMe 스토리지 어레이, 400 Gbps 네트워크 패브릭에 힘입어 연평균 성장률(CAGR) 8.16%로 가장 빠르게 성장하는 부문입니다. 하이퍼스케일 고객들은 직접-투-칩(DTC) 방식의 액체 매니폴드가 필요한 고밀도 랙을 표준화하고 있으며, 이로 인해 스테인리스 스틸 배관 및 이중화된 냉각 펌프에 대한 수요가 증가하고 있습니다. 컨설팅, 시운전, 시설 관리 등의 서비스는 규제 준수 및 PUE 최적화를 보장함으로써 부가가치를 제공합니다. 라틴아메리카 전역의 증권거래소에서 탄소 공시 기준이 엄격해짐에 따라, 에너지 효율 컨설팅 분야에서 라틴아메리카의 데이터센터 건설 시장 점유율이 상승하고 있습니다.
2025년, 라틴아메리카의 데이터센터 건설 시장에서 Tier III 사이트는 61.10%의 점유율을 차지하며, 99.982%의 가용성과 관리 가능한 자본 지출(CAPEX)의 균형을 실현했습니다. 은행, 보험사, 퍼블릭 클라우드 사업자는 짧은 유지보수 시간을 허용할 수 있는 핵심 워크로드에 대해 이 수준을 선택하고 있습니다. 반면, 컨텐츠 전송 네트워크나 지역 엣지 노드의 경우, 비용을 절감하면서도 노드를 사용자와 가까운 곳에 배치하기 위해 Tier II가 도입되는 경우가 많습니다.
하이퍼스케일러와 핀테크 플랫폼이 99.995%의 서비스 수준 보장을 요구하는 것을 배경으로, Tier IV 구축은 2031년까지 연평균 성장률(CAGR) 8.55%로 성장할 전망입니다. 여러 개의 독립적인 배전 경로, 내결함성 냉각 장치, 병렬로 유지보수가 가능한 발전기는 자본 예산을 최대 60%까지 끌어올리지만, 고객은 가동 시간과 관련된 수익 조항을 충족하기 위해 이 추가 비용을 감수하고 있습니다. 건설업체들은 설계 초기 단계에서 인증 기관과 협력함으로써, 신규 진입 업체들을 괴롭혀 온 후기 단계의 개조 비용을 피하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the Latin America data center construction market size is expected to grow from USD 5.59 billion in 2025 to USD 6.05 billion in 2026 and is forecast to reach USD 8.96 billion by 2031 at 8.19% CAGR over 2026-2031.
This report is Segmented by Infrastructure (Electrical Infrastructure, Mechanical Infrastructure, and More), Tier Standard (Tier I and II, Tier III, and More), End User (Banking Financial Services & Insurance, IT & Telecommunications, and More), Data Center Type (Colocation, Hyperscale, and More), and Geography (Brazil, Mexico, and More). Forecasts are in USD.
Latin America Data Center Construction Market Trends and Insights
Accelerating cloud, AI and big-data workloads
Artificial-intelligence applications now demand three to five times the power density of legacy computing, compelling operators to redesign thermal architectures and electrical topologies. Microsoft's USD 2.7 billion Brazil investment and Scala's USD 50 billion AI City illustrate the scale of new requirements. Liquid-cooling adoption accelerates, with locally manufactured Delta Cube systems reducing energy usage in ODATA sites. Regional policy makers regard AI infrastructure as a pillar of digital competitiveness, prompting expedited permits and targeted tax breaks. Contractors report surging bids for high-density MEP packages, and suppliers of busway, pumps, and plate-heat exchangers scale up regional production footprints.
Hyperscale campus build-outs by U.S. cloud majors
Amazon Web Services, Microsoft Azure, and Google Cloud collectively earmark more than USD 10 billion for Latin America by 2030. Multi-gigawatt campuses in Sao Paulo, Queretaro, and Bogota require redundant 400 kV utility feeds, advanced fire suppression, and prefabricated power rooms that cut commissioning cycles to 12-18 months. Regional fiber conglomerate V.tal alone budgets USD 1 billion to deliver hyperscale-ready shells in Brazil. The build-to-suit model favors EPC firms proficient in integrated design-build, and demand spills into secondary metros as power availability tightens in first-tier cities.
Grid-power bottlenecks and surging electricity tariffs
Mexico struggles with 18-month utility-interconnection queues, pushing developers to procure diesel generation that adds up to 25% to project CAPEX and inflates operating expenses. Argentina's macro-economic volatility amplifies tariff risk, while localized transmission congestion in Sao Paulo forces developers toward Campinas and Porto Alegre. AI workloads multiply power density, stressing grids originally designed for commercial office loads. Operators increasingly sign 15-year renewable PPAs to secure predictable pricing, but smaller enterprises lack the balance-sheet to pursue such deals, slowing adoption in mid-market segments.
Other drivers and restraints analyzed in the detailed report include:
- 5G-driven edge-DC demand in secondary LATAM metros
- Sovereign-cloud and data-residency regulations
- Scarcity of Tier-III/IV-certified MEP labor
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Mechanical infrastructure contributed 37.35% to the Latin America Data Center Construction market size in 2025, as hot-humid conditions across Brazil, Peru, and Colombia require robust chilled-water loops, evaporative cooling, and custom containment systems. Power distribution units, switchgear, and UPS arrays within electrical infrastructure stay essential for banking and telecom uptime mandates. General construction captures resilient shell-and-core outlays, including seismic bracing and hurricane-rated envelopes that safeguard mission-critical halls.
IT infrastructure is the fastest-growing category with an 8.16% CAGR, driven by servers optimized for AI inference, NVMe storage arrays, and 400 Gbps networking fabric. Hyperscale clients standardize on high-density racks requiring direct-to-chip liquid manifolds, which boosts demand for stainless-steel piping and redundant coolant pumps. Services such as consulting, commissioning, and facility management add value by ensuring regulation compliance and PUE optimization. The Latin America Data Center Construction market share within energy-efficiency consulting rises as carbon disclosure norms tighten in stock exchanges across the region.
Tier III sites held 61.10% of the Latin America Data Center Construction market share in 2025, balancing 99.982% availability against manageable capex. Banks, insurers, and public clouds select this level for core workloads that tolerate brief maintenance windows. Conversely, content-delivery networks and regional edge nodes often deploy Tier II to limit cost while placing nodes closer to users.
Tier IV construction will grow 8.55% CAGR through 2031 on the back of hyperscalers and fintech platforms seeking 99.995% service-level commitments. Multiple independent distribution paths, fault-tolerant chillers, and concurrently maintainable generators inflate capital budgets by up to 60%, yet clients accept the premium to satisfy uptime-linked revenue clauses. Builders partner with certification bodies early in design to avoid late-stage retrofit costs that have plagued first-time entrants.
Complete Report Scope:
- By Infrastructure
- By Electrical Infrastructure
- Power Distribution Solutions
- Power Distribution Unit
- Switchgears
- Others Electrical Infrastructure
- Power Backup Solutions
- UPS
- Generators
- Power Distribution Solutions
- By Mechanical Infrastructure
- Cooling Systems
- Liquid-based Cooling
- Air-based Cooling
- Racks and Cabinets
- Other Mechanical Infrastructure
- Cooling Systems
- By IT Infrastructure
- Servers
- Storage
- Other IT Infrastructure
- General Construction
- Services
- Design and Consulting
- Integration
- Support and Maintenance
- By Electrical Infrastructure
- By Tier Standard
- Tier I and II
- Tier III
- Tier IV
- By End-User Industry
- Banking, Financial Services and Insurance
- IT and Telecommunications
- Government and Defense
- Healthcare
- Other End Users
- By Data Center Type
- Colocation Data Centers
- Hyperscale / Self-built Data Centers
- Others (Enterprise / Edge / Modular)
- By Geography
- Brazil
- Chile
- Argentina
- Rest of Latin America
List of Companies Covered in this Report:
- AECOM
- Turner Construction Company
- DPR Construction
- Jacobs Solutions Inc.
- Fluor Corporation
- Skanska AB (Latin America)
- Ferrovial S.A.
- Grupo ACS (Dragados)
- ACCIONA Construccion
- Andrade Gutierrez Engenharia
- Camargo Correa Infra
- Novonor (Odebrecht Engenharia)
- Queiroz Galvao S.A.
- Techint EandC
- Sacyr Ingenieria e Infraestructuras
- Mota-Engil LATAM
- Constructora Norberto Odebrecht LatAm
- Grupo Carso Infraestructura
- COSAPI Ingenieria y Construccion
- Constructora Colpatria
- Grupo Marhnos
- Constructora Sudamericana
- Ghella S.p.A.
- Besix Watpac
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerating cloud, AI and big-data workloads
- 4.2.2 Hyperscale campus build-outs by US cloud majors
- 4.2.3 5G-driven edge-DC demand in secondary LATAM metros
- 4.2.4 Sovereign-cloud and data-residency regulations
- 4.2.5 Power-purchase-agreement (PPA) availability for renewables
- 4.2.6 Modular and prefabricated construction adoption
- 4.3 Market Restraints
- 4.3.1 Grid-power bottlenecks and surging electricity tariffs
- 4.3.2 Scarcity of Tier-III/IV-certified MEP labour
- 4.3.3 Water-stress curbing liquid-cooling deployments
- 4.3.4 Lengthy environmental licensing and community opposition
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Key Latin America Data Center Construction Statistics
- 4.8.1 Data Centers Total Installed Capacity (MW) in the Latin America, 2023 and 2024
- 4.8.2 Total IT Load Under Construction in the Latin America, MW, 2025 - 2030
- 4.8.3 Average Capex and Opex for the Latin America Data Center Construction
- 4.8.4 Top Capex Spenders on Data Center Infrastructure in Latin America
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Infrastructure
- 5.1.1 By Electrical Infrastructure
- 5.1.1.1 Power Distribution Solutions
- 5.1.1.1.1 Power Distribution Unit
- 5.1.1.1.2 Switchgears
- 5.1.1.1.3 Others Electrical Infrastructure
- 5.1.1.2 Power Backup Solutions
- 5.1.1.2.1 UPS
- 5.1.1.2.2 Generators
- 5.1.1.1 Power Distribution Solutions
- 5.1.2 By Mechanical Infrastructure
- 5.1.2.1 Cooling Systems
- 5.1.2.1.1 Liquid-based Cooling
- 5.1.2.1.2 Air-based Cooling
- 5.1.2.2 Racks and Cabinets
- 5.1.2.3 Other Mechanical Infrastructure
- 5.1.2.1 Cooling Systems
- 5.1.3 By IT Infrastructure
- 5.1.3.1 Servers
- 5.1.3.2 Storage
- 5.1.3.3 Other IT Infrastructure
- 5.1.4 General Construction
- 5.1.5 Services
- 5.1.5.1 Design and Consulting
- 5.1.5.2 Integration
- 5.1.5.3 Support and Maintenance
- 5.1.1 By Electrical Infrastructure
- 5.2 By Tier Standard
- 5.2.1 Tier I and II
- 5.2.2 Tier III
- 5.2.3 Tier IV
- 5.3 By End-User Industry
- 5.3.1 Banking, Financial Services and Insurance
- 5.3.2 IT and Telecommunications
- 5.3.3 Government and Defense
- 5.3.4 Healthcare
- 5.3.5 Other End Users
- 5.4 By Data Center Type
- 5.4.1 Colocation Data Centers
- 5.4.2 Hyperscale / Self-built Data Centers
- 5.4.3 Others (Enterprise / Edge / Modular)
- 5.5 By Geography
- 5.5.1 Brazil
- 5.5.2 Chile
- 5.5.3 Argentina
- 5.5.4 Rest of Latin America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Share Analysis
- 6.2 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.2.1 AECOM
- 6.2.2 Turner Construction Company
- 6.2.3 DPR Construction
- 6.2.4 Jacobs Solutions Inc.
- 6.2.5 Fluor Corporation
- 6.2.6 Skanska AB (Latin America)
- 6.2.7 Ferrovial S.A.
- 6.2.8 Grupo ACS (Dragados)
- 6.2.9 ACCIONA Construccion
- 6.2.10 Andrade Gutierrez Engenharia
- 6.2.11 Camargo Correa Infra
- 6.2.12 Novonor (Odebrecht Engenharia)
- 6.2.13 Queiroz Galvao S.A.
- 6.2.14 Techint EandC
- 6.2.15 Sacyr Ingenieria e Infraestructuras
- 6.2.16 Mota-Engil LATAM
- 6.2.17 Constructora Norberto Odebrecht LatAm
- 6.2.18 Grupo Carso Infraestructura
- 6.2.19 COSAPI Ingenieria y Construccion
- 6.2.20 Constructora Colpatria
- 6.2.21 Grupo Marhnos
- 6.2.22 Constructora Sudamericana
- 6.2.23 Ghella S.p.A.
- 6.2.24 Besix Watpac
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment