

|
시장보고서
상품코드
2125535
싱가포르의 ICT : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Singapore ICT - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
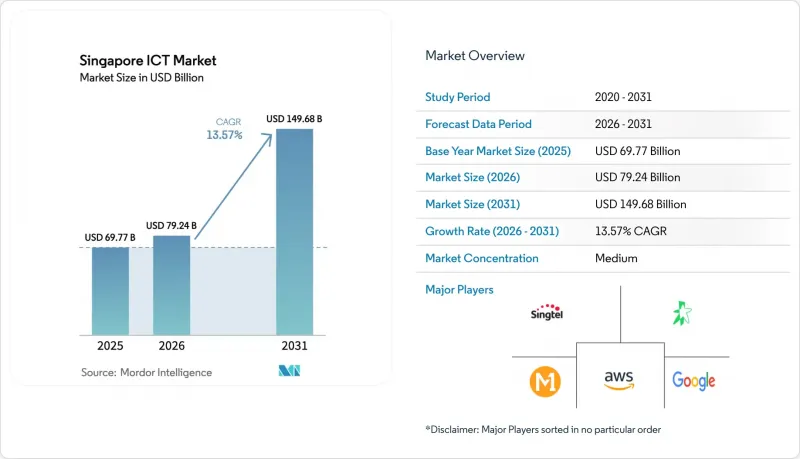
에 의하면, 싱가포르의 ICT 시장 규모는 2025년 697억 7,000만 달러로 평가되었습니다. 2026년에는 792억 4,000만 달러로 확대되어 2026년부터 2031년에 걸쳐 CAGR 13.57%로 성장을 지속하여, 2031년에는 1,496억 8,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 유형(IT 하드웨어, IT 소프트웨어 등), 최종 사용자 기업 규모(중소기업·대기업), 배포 모델(On-Premise 등), 최종 사용자 업종(정부·공공 행정 등)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
싱가포르의 ICT 시장 동향 및 인사이트
정부의 ‘스마트 네이션’ 관련 지출 급증
‘스마트 네이션 2.0’은 싱가포르를 단순한 디지털 도입에서 ‘디지털 퍼스트’ 거버넌스로 전환시켰으며, 2024 회계연도에는 33억 달러를 사이버 보안, 데이터 플랫폼, 현대화된 인프라에 투자했습니다. 이러한 지출로 인해 분석 엔진, 엣지 디바이스, 실시간 처리 도구의 조달이 가속화되어 공공 부문을 훨씬 뛰어넘는 수요를 불러일으키고 있습니다. 이러한 기준을 반영한 규제 요건으로 인해, 특히 금융 및 의료 분야의 민간 기업들은 레거시 시스템의 업그레이드를 서둘러야 하는 상황에 처해 있습니다. API 오케스트레이션 및 크로스 플랫폼 보안을 전문으로 하는 벤더들은 다년간의 대규모 계약을 직접 수주할 기회를 얻고 있으며, 상호 운용 가능한 프레임워크 덕분에 산업 간 통합 과정에서 발생하는 마찰이 완화되고 있습니다.
기업의 ‘클라우드 퍼스트’ 정책
‘클라우드 우선’ 정책으로 인해 인프라 계획 방식이 완전히 바뀌었으며, 클라우드 워크로드는 17.7% 증가한 반면, On-Premise 배포는 11.2% 증가에 그쳤습니다. 멀티클라우드 전략은 벤더 종속성을 완화하고 데이터 주권에 관한 규정을 충족시킴으로써 35억 달러 규모의 국내 클라우드 시장을 견인하고 있습니다. 중소기업은 구독형 AI, 분석, 자동화를 활용하여 대기업 수준의 기능을 확보하고 있으며, 가장 빠른 도입을 추진하고 있습니다. 분산 환경을 규제 준수 요건에 부합하도록 하기 위한 통합 가시성 대시보드, 하이브리드 연결 패브릭, 자동화된 정책 거버넌스에 대한 파생 수요도 발생하고 있습니다.
숙련된 디지털 인재 부족
2,800명에서 4,400명에 달하는 사이버 보안 전문가 부족으로 인해 도입 일정이 지연되고 인건비가 상승하고 있습니다. 한편, 보안 수요는 2029년까지 48억 2,000만 달러에 달할 것으로 예측됩니다. 이러한 인력 부족은 AI 엔지니어와 클라우드 아키텍트에게도 미치고 있으며, 중소기업은 보상 측면에서 다국적 기업과 경쟁할 수밖에 없는 상황에 처해 있습니다. 4,500명의 학습자를 대상으로 하는 IBM의 ‘SkillsBuild’를 비롯한 정부 지원 기술 향상 프로그램은 인력 부족을 서서히 해소하는 데 그칠 뿐입니다. 따라서 기업들은 희소한 전문가에 대한 의존도를 낮추기 위해 로우코드 플랫폼, AI를 활용한 개발, 매니지드 서비스로 무게중심을 옮기고 있습니다.
부문별 분석
2025년 싱가포르의 ICT 시장 규모 중 IT 인프라가 25.86%를 차지했으며, 이는 데이터센터, 네트워크 장비, 서버 용량에 대한 지속적인 투자가 뒷받침되고 있음을 보여줍니다. 이 부문은 AWS의 120억 달러 규모 계획 등 하이퍼스케일 확장에 대한 노력의 혜택을 받고 있지만, 가상화로 인해 서버 랙 밀도가 높아짐에 따라 전년 대비 성장률은 둔화되고 있습니다. IT 소프트웨어는 클라우드 네이티브 플랫폼, AI 툴체인, 워크플로우 자동화 제품군에 힘입어 연평균 성장률(CAGR) 16.35%를 기록하며 다른 모든 카테고리를 능가하는 성장세를 보이고 있습니다. 이러한 소프트웨어로의 전환에 따라 컨테이너 오케스트레이션, 마이크로서비스 보안, 애자일 통합 서비스에 대한 수요가 증가하고 있습니다. 인프라와 용도의 병행 확장이 균형 잡힌 성장의 기반이 되고 있습니다. 기업들은 기업 소프트웨어에 대해 구독형 가격 책정을 점점 더 많이 채택하고 있으며, 이로 인해 자본 지출의 급증은 억제되고 현금 흐름은 안정화되고 있습니다. 상품화가 진행됨에 따라 하드웨어의 이익률은 축소되는 추세이지만, 특수 AI 가속기나 엣지 디바이스에는 여전히 프리미엄 가격이 책정되고 있습니다. SAP 등 주요 벤더들은 싱가포르에 연구개발(R&D) 거점을 마련하고 있으며, 업계 고유의 AI 모델을 현지 이용 사례에 적용하는 ‘디지털 혁신 가속기’가 그 대표적인 예입니다. 대용량 인프라와 첨단 소프트웨어의 시너지 효과로 선순환이 형성되어, 싱가포르의 ICT 시장은 상승 궤도를 유지하고 있습니다.
2025년, 대기업은 싱가포르 ICT 시장 점유율의 66.78%를 차지하며, 예산과 사내 인재를 활용하여 복잡하고 다방면에 걸친 디지털화를 추진했습니다. 그러나 많은 기업이 이미 1단계 변혁을 완료했기 때문에 성장률은 12.84%로 둔화되고 있습니다. 대조적으로, 중소기업은 도입 주기를 단축하는 정부의 보조금과 클라우드 구독 서비스의 지원에 힘입어 연평균 성장률(CAGR) 14.88%로 성장을 지속하고, 있습니다. 턴키형 AI 서비스의 이용 기회가 확대됨에 따라, 중소기업은 고가의 하드웨어를 보유하지 않고도 챗봇, 분석, 로봇 프로세스 자동화(RPA)를 통합할 수 있게 되었습니다. 또한, 인재 육성 이니셔티브를 통해 중소기업에 대한 디지털 인재 공급이 지속적으로 확보되고 있습니다. IBM의 ‘SkillsBuild’는 데이터 분석 및 사이버 보안에 관한 무료 인증 과정을 제공하는 대표적인 사례입니다. ‘Productivity Solutions Grant(생산성 솔루션 보조금)’와 같은 재정적 인센티브를 통해 대상 기술 투자의 최대 70%가 환급되어, 도입 조건의 공정성이 더욱 높아지고 있습니다. 중소기업이 규모를 확대함에 따라, 관리형 서비스 제공업체(MSP) 및 부가가치 재판매업체에게 큰 고객 기반을 형성하며, 싱가포르의 ICT 시장을 지탱하는 다양한 벤더 생태계를 강화하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 동향
KTH 26.09.16According to Mordor Intelligence, the Singapore ICT market size is expected to grow from USD 69.77 billion in 2025 to USD 79.24 billion in 2026 and is forecast to reach USD 149.68 billion by 2031 at 13.57% CAGR over 2026-2031.
This report is Segmented by Type (IT Hardware, IT Software, and More), End-User Enterprise Size (Small and Medium Enterprises and Large Enterprises), Deployment Model (On-Premise, and More), and End-User Industry (Government and Public Administration, and More). The Market Forecasts are Provided in Terms of Value (USD).
Singapore ICT Market Trends and Insights
Government Smart-Nation Expenditure Surge
Smart Nation 2.0 moves Singapore from digital adoption toward digital-first governance, channeling USD 3.3 billion in fiscal 2024 into cybersecurity, data platforms, and modernized infrastructure. The outlay accelerates procurement of analytics engines, edge devices, and real-time processing tools, catalyzing demand far beyond the public sector. Regulatory requirements that mirror these standards push private organizations, especially in finance and healthcare, to upgrade legacy systems. Vendors specializing in API orchestration and cross-platform security gain direct access to large multi-year contracts, while interoperable frameworks reduce integration friction across verticals.
Enterprise Cloud-first Mandates
Cloud-first policies have flipped infrastructure planning, with cloud workloads growing 17.7% against 11.2% for on-premise deployments. Multi-cloud strategies lessen vendor lock-in and satisfy data-sovereignty rules, prompting a USD 3.5 billion domestic cloud market. SMEs drive the fastest uptake, using subscription-based AI, analytics, and automation to match big-company capabilities. Secondary demand is emerging for unified observability dashboards, hybrid connectivity fabrics, and automated policy governance that keep distributed environments in regulatory compliance.
Scarcity of Skilled Digital Talent
A shortage of 2,800 to 4,400 cybersecurity professionals shackles rollout schedules and elevates salary costs, even as security demand is set to hit USD 4.82 billion by 2029. The gap extends to AI engineers and cloud architects, forcing SMEs to compete with multinationals on compensation. Government-backed upskilling programs, including IBM's SkillsBuild, which targets 4,500 learners, will narrow deficits only gradually. Firms therefore pivot to low-code platforms, AI-assisted development, and managed services that reduce reliance on scarce specialists.
Other drivers and restraints analyzed in the detailed report include:
- Digital Bank Licenses Boost BFSI Tech Spend
- National AI Compute Resource Roll-out
- Escalating Cyber-attack Surface
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
IT infrastructure owned 25.86% of Singapore ICT market size in 2025, underlining continued investment in data centers, networking gear, and server capacity . The segment benefits from hyperscale expansion commitments such as AWS's USD 12 billion plan, but year-on-year growth is moderating as virtualization densifies server racks. IT software outpaces all other categories with a 16.35% CAGR, propelled by cloud-native platforms, AI toolchains, and workflow automation suites. This software pivot lifts demand for container orchestration, micro-services security, and agile integration services. Parallel expansion of infrastructure and applications underpins a balanced growth profile. Companies increasingly adopt subscription pricing for enterprise software, flattening capex spikes and smoothing cash flows. Hardware margins tighten amid commoditization, though specialized AI accelerators and edge devices command premiums. Major vendors such as SAP anchor R&D in Singapore, exemplified by its Digital Innovation Accelerator that aligns industry-specific AI models with local use cases . The interplay of high-capacity infrastructure with advanced software creates a virtuous cycle that keeps the Singapore ICT market on its upward trajectory.
Large enterprises held 66.78% of Singapore ICT market share in 2025, leveraging budgets and in-house talent to execute complex, multi-domain digitization. Growth, however, is slowing to 12.84% as many have already completed first-wave transformations. SMEs, in contrast, are posting a 14.88% CAGR, driven by government grants and cloud subscriptions that compress deployment cycles. The widening availability of turnkey AI services empowers small firms to integrate chatbots, analytics, and robotic process automation without owning expensive hardware. Training initiatives keep the pipeline of digital talent flowing to smaller companies. IBM's SkillsBuild is one example that provides free certification tracks for data analytics and cybersecurity . Financial incentives such as the Productivity Solutions Grant reimburse up to 70% of qualifying tech investments, further equalizing adoption conditions. As SMEs scale, they form a sizeable customer base for managed-service providers and value-added resellers, reinforcing a diversified vendor ecosystem that underpins the Singapore ICT market.
Complete Report Scope:
- By Type
- IT Hardware
- Computer Hardware
- Networking Equipment
- Peripherals
- IT Software
- IT Services
- Managed Services
- Business Process Services
- Business Consulting Services
- Cloud Services
- IT Infrastructure
- Communication Services
- IT Hardware
- By End-User Enterprise Size
- Small and Medium Enterprises
- Large Enterprises
- By Deployment Model
- On-premise
- Cloud
- Hybrid
- By End-user Industry Vertical
- Government and Public Administration
- BFSI
- Energy and Utilities
- Retail, E-commerce and Logistics
- Manufacturing and Industry 4.0
- Healthcare and Life Sciences
- Oil and Gas (Up-, Mid-, Down-stream)
- Gaming and Esports
- Other Verticals
List of Companies Covered in this Report:
- Amazon Web Services (AWS) Singapore
- International Business Machines Corporation (IBM Singapore Pte. Ltd.)
- Cognizant Technology Solutions Asia Pacific Pte. Ltd.
- Micron Semiconductor Asia Operations Pte. Ltd.
- SAP Asia Pte. Ltd.
- Wipro Ltd. (Singapore)
- Hewlett Packard Enterprise Singapore Pte. Ltd.
- Intel Technology Asia Pte. Ltd.
- Singapore Telecommunications Ltd. (Singtel)
- StarHub Ltd.
- M1 Ltd.
- TPG Telecom Pte. Ltd. (SIMBA Telecom)
- NCS Pte. Ltd.
- NEC Asia Pacific Pte. Ltd.
- Dell Technologies Singapore Pte. Ltd.
- Google Asia Pacific Pte. Ltd.
- Microsoft Operations Pte. Ltd. (Microsoft Singapore)
- Equinix Singapore Pte. Ltd.
- Alibaba Cloud (Singapore) Private Limited
- Palo Alto Networks (Singapore) Pte. Ltd.
- Check Point Software Technologies (Singapore) Pte. Ltd.
- Trend Micro (Singapore) Pte. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Market Definition and Study Assumptions
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government Smart-Nation Expenditure Surge
- 4.2.2 Rapid 5G Roll-out and Adoption
- 4.2.3 Enterprise Cloud-first Mandates
- 4.2.4 Digital Bank Licences Boost BFSI Tech Spend
- 4.2.5 National AI Compute Resource (NACR) Roll-out
- 4.2.6 Green-Powered Hyperscale Data-centre Incentives
- 4.3 Market Restraints
- 4.3.1 Scarcity of Skilled Digital Talent
- 4.3.2 Escalating Cyber-attack Surface
- 4.3.3 Power-grid Capacity Caps on New DC Builds
- 4.3.4 Wage Inflation from Foreign-Labour Curbs
- 4.4 Value Chain Analysis
- 4.5 Evaluation of Critical Regulatory Framework
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macro-economic Factors
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 IT Hardware
- 5.1.1.1 Computer Hardware
- 5.1.1.2 Networking Equipment
- 5.1.1.3 Peripherals
- 5.1.2 IT Software
- 5.1.3 IT Services
- 5.1.3.1 Managed Services
- 5.1.3.2 Business Process Services
- 5.1.3.3 Business Consulting Services
- 5.1.3.4 Cloud Services
- 5.1.4 IT Infrastructure
- 5.1.5 Communication Services
- 5.1.1 IT Hardware
- 5.2 By End-User Enterprise Size
- 5.2.1 Small and Medium Enterprises
- 5.2.2 Large Enterprises
- 5.3 By Deployment Model
- 5.3.1 On-premise
- 5.3.2 Cloud
- 5.3.3 Hybrid
- 5.4 By End-user Industry Vertical
- 5.4.1 Government and Public Administration
- 5.4.2 BFSI
- 5.4.3 Energy and Utilities
- 5.4.4 Retail, E-commerce and Logistics
- 5.4.5 Manufacturing and Industry 4.0
- 5.4.6 Healthcare and Life Sciences
- 5.4.7 Oil and Gas (Up-, Mid-, Down-stream)
- 5.4.8 Gaming and Esports
- 5.4.9 Other Verticals
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Amazon Web Services (AWS) Singapore
- 6.4.2 International Business Machines Corporation (IBM Singapore Pte. Ltd.)
- 6.4.3 Cognizant Technology Solutions Asia Pacific Pte. Ltd.
- 6.4.4 Micron Semiconductor Asia Operations Pte. Ltd.
- 6.4.5 SAP Asia Pte. Ltd.
- 6.4.6 Wipro Ltd. (Singapore)
- 6.4.7 Hewlett Packard Enterprise Singapore Pte. Ltd.
- 6.4.8 Intel Technology Asia Pte. Ltd.
- 6.4.9 Singapore Telecommunications Ltd. (Singtel)
- 6.4.10 StarHub Ltd.
- 6.4.11 M1 Ltd.
- 6.4.12 TPG Telecom Pte. Ltd. (SIMBA Telecom)
- 6.4.13 NCS Pte. Ltd.
- 6.4.14 NEC Asia Pacific Pte. Ltd.
- 6.4.15 Dell Technologies Singapore Pte. Ltd.
- 6.4.16 Google Asia Pacific Pte. Ltd.
- 6.4.17 Microsoft Operations Pte. Ltd. (Microsoft Singapore)
- 6.4.18 Equinix Singapore Pte. Ltd.
- 6.4.19 Alibaba Cloud (Singapore) Private Limited
- 6.4.20 Palo Alto Networks (Singapore) Pte. Ltd.
- 6.4.21 Check Point Software Technologies (Singapore) Pte. Ltd.
- 6.4.22 Trend Micro (Singapore) Pte. Ltd.
7 MARKET OPPORTUNITIES AND FUTURE TRENDS
- 7.1 White-space and Unmet-need Assessment


