|
시장보고서
상품코드
2098490
헬스케어용 그린 IT 소프트웨어 시장 : 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Green IT Software For Healthcare - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
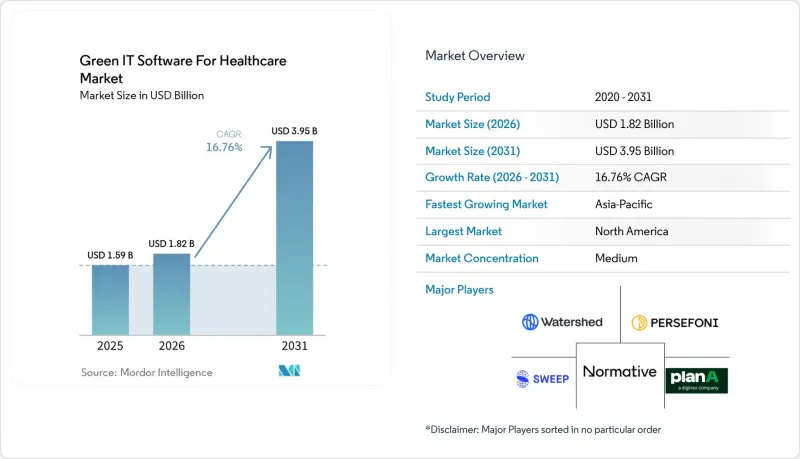
에 의하면, 헬스케어용 그린 IT 소프트웨어 시장 규모는 2025년 15억 9,000만 달러에서 2026년에는 18억 2,000만 달러로 확대되어 2031년까지 39억 5,000만 달러에 이를 것으로 예상되고 있어 2026년부터 2031년까지 CAGR 16.76%로 성장할 전망입니다.
본 보고서는 구성 요소(소프트웨어 및 서비스), 배포 방식(클라우드 기반, On-Premise형, 하이브리드형), 조직 규모(대기업 및 중소기업), 용도(탄소 발자국, 에너지 최적화, ESG 보고, IT 인프라), 최종 사용자(병원, 외래 진료, 영상 진단, 보험사, 생명과학), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 헬스케어용 그린 IT 소프트웨어 시장 동향 및 인사이트
전체 의료 디지털 자산에서 에너지 비용 상승 압력
영상 저장, 임상용 서버 및 연결된 디지털 워크플로우 전반에 걸친 전력 사용량 증가로 인해, 헬스케어용 그린 IT 소프트웨어 시장은 의료 기관 경영진에게 더욱 시급한 과제가 되고 있습니다. 『European Radiology』 저널의 2025년 연구에 따르면, 장기적인 CT 데이터 저장은 스토리지 시스템, 서버, 네트워크 인프라 전반에 걸쳐 막대한 전력을 소비하고 있으며, 이는 병원에 지속가능성을 위한 노력에 대한 명확한 운영 기준을 제시하고 있습니다. 디지털 의료가 확대됨에 따라 에너지 관리와 탄소 배출량 추적은 별도의 팀이 수행하는 것이 아니라 동일한 운영 워크플로우 내에서 이루어지고 있습니다. 이러한 변화로 인해 자산 선정, 워크로드 배치, 보고서 출력을 단일 시스템에 통합할 수 있는 플랫폼이 유리해지고 있습니다. 그 직접적인 효과로, 에너지가 어디에서 소비되고 있는지, 또한 운영상의 변경을 통해 비용과 배출량을 어떻게 모두 절감할 수 있는지를 보여줄 수 있는 소프트웨어에 대한 수요가 증가하고 있습니다.
의료 시스템 조달과 연계된 탄소 배출량 보고 요건
조달 규정 변경에 따라, 헬스케어용 그린 IT 소프트웨어는 임의 지출에서 계약 연계 지출로 전환되고 있습니다. 2026년 4월 6일부터 NHS 공급망은 공급업체에게 ‘에버그린 지속가능성 공급업체 평가 레벨 1’을 완료하고, 스코프 1, 스코프 2, 그리고 관련 스코프 3 배출량을 포괄하는 PPN 006 준수 ‘탄소 감축 계획’ 수립을 의무화했습니다. 이 요건이 중요한 이유는 탄소 데이터 수집이 일반적인 공급업체 자격 심사, 계약 갱신 및 입찰 활동에 통합되기 때문입니다. 『Journal of Medical Internet Research』 저널도 영국의 1차 진료 분야에서 실증되지 않은 생성형 AI가 보고의 공백을 초래하고 있다고 보고했습니다. 이는 AI 관련 배출량이 현재의 공개 정보에서 일관되게 파악되지 않고 있기 때문입니다. 조달 기준과 공시 기대치가 모두 엄격해짐에 따라, 감사 대응이 가능한 보고를 지원하는 플랫폼은 의료 예산 시장 진입 경로를 더욱 확실하게 확보할 수 있게 될 것입니다.
임상 시스템과 비임상 시스템에 걸쳐 분산된 지속가능성 데이터
지속가능성 관련 기록이 임상, 시설, 조달 및 기업 소프트웨어 시스템에 분산되어 있기 때문에 데이터의 분산은 헬스케어용 그린 IT 소프트웨어 시장의 가장 큰 장벽으로 남아 있습니다. 병원에서는 에너지, 자산, 운영 데이터를 별도의 환경에서 관리하는 경우가 많아, 일관된 배출량 기준선 수립이 지연되고 있습니다. 이러한 취약한 출발점으로 인해 보고가 더욱 어려워지며, 특히 조직이 여러 거점에 걸친 단일 뷰를 필요로 하는 경우 플랫폼 도입 주기가 길어집니다. Sana Kliniken AG가 2025년 ESG 데이터 관리를 위해 Osapiens로 전환하기로 결정한 것은 대규모 운영 사업자들이 서로 연계되지 않은 워크플로우에 의존하기보다는 엔터프라이즈 시스템을 구축하려는 이유를 여실히 보여줍니다. 데이터 모델과 인터페이스가 더욱 표준화되기 전까지는 헬스케어용 그린 IT 소프트웨어의 도입이 여러 거점을 보유한 의료 제공업체나 중규모 의료 기관에서 주춤할 것입니다.
부문 분석
2025년에는 소프트웨어가 시장의 58%를 차지했으나, 서비스 부문은 2031년까지 연평균 성장률(CAGR) 18.12%를 나타낼 것으로 예측됩니다. 의료 분야의 구매자들은 일회성 컨설팅 업무가 아닌, 문서화되고 지속적으로 업데이트되는 플랫폼을 필요로 하기 때문에 소프트웨어는 여전히 구조적 기반으로서의 지위를 유지하고 있습니다. 이러한 지위는 보고 기간 동안 재현 가능한 데이터 수집, 감사 지원 및 워크플로우의 일관성을 요구하는 공시 요건에 의해 더욱 강화되고 있습니다. 헬스케어용 그린 IT 소프트웨어 분야에서 이러한 점은 소프트웨어를 기타 도입 및 자문 서비스가 구축되는 기반 계층으로 자리매김하게 합니다.
서비스 분야는 여전히 가장 빠른 성장이 예상됩니다. 이는 헬스케어용 그린 IT 소프트웨어 시장의 많은 구매자에게 통합, 설정, 검증 및 보고 지원이 여전히 필수적이기 때문입니다. 공시 범위가 공급망 데이터, AI 관련 배출량 및 여러 프레임워크에 걸친 보고로 확대됨에 따라, 조직은 소프트웨어의 산출물을 실용적인 규정 준수 기록으로 변환하기 위한 지원을 더욱 필요로 하고 있습니다. SAP는 2026년 5월, 자사의 새로운 지속가능성 AI 에이전트를 통해 포장 관련 규정 준수 처리 시간을 50% 이상 단축하고, 시나리오 시뮬레이션 시간을 1일에서 20분으로 단축할 수 있다고 발표했습니다. 이는 지금까지보다 더 깊은 서비스 관여가 필요했던 업무를 공급업체가 어떻게 자동화하고 있는지를 보여줍니다. 이러한 추세를 통해 단기적으로는 서비스 수요가 계속해서 견조할 것, 해당 업무의 상당 부분은 점차 자동화를 통해 형성되어 갈 것임을 시사합니다.
2025년에는 헬스케어용 그린 IT 소프트웨어 시장 규모의 64%를 클라우드 기반 도입이 차지했으나, 하이브리드 도입은 2031년까지 연평균 성장률(CAGR) 17.50%를 나타낼 것으로 예측됩니다. 클라우드가 여전히 가장 큰 도입 형태를 유지한 것은 지속가능성 분석을 에너지 소비가 많은 로컬 인프라에서 이전하려는 움직임과 부합하기 때문입니다. 하이브리드 방식의 성장이 빠른 이유는 많은 의료 기관이 여전히 임상 시스템, 빌딩 관리 시스템 및 기밀성이 높은 데이터 환경에 대한 On-Premise 연결을 필요로 하기 때문입니다. 헬스케어용 그린 IT 소프트웨어 시장에서는 중앙 집중형 보고서 작성 도구와 관리형 On-Premise 데이터 액세스를 결합한 아키텍처에 대한 지속적인 수요가 발생하고 있습니다.
On-Premise 배포의 상대적 비중은 점차 낮아지고 있지만, 엄격한 지연 시간, 개인정보 보호 및 내부 통제 요건이 여전히 요구되는 상황에서는 여전히 중요한 역할을 수행하고 있습니다. 2025년 3월 구라시키 중앙병원이 Nutanix Cloud Platform으로 마이그레이션한 사례는 의료 제공업체가 핵심 시스템을 현대화하면서 더 광범위한 IT 지속가능성 목표를 지원할 수 있음을 보여주었습니다. 실제로 많은 구매자가 단계적 전환 모델을 채택하고 있기 때문에 레거시 시스템과 클라우드 중 하나를 선택해야 하는 단순한 이분법적 상황은 더 이상 발생하지 않습니다. 따라서 헬스케어용 그린 IT 소프트웨어 분야에서는 기존 임상 업무에 지장을 주지 않으면서 혼합 환경을 지원할 수 있는 벤더가 우위를 점하게 됩니다.
지역별 분석
2025년, 북미는 헬스케어용 그린 IT 소프트웨어 시장 점유율의 38%를 차지했습니다. 이 지역이 주도적인 위치를 차지한 것은 기업 소프트웨어 공급업체의 강력한 기반, 대규모 통합 의료 시스템, 그리고 성숙한 디지털 인프라가 결합되어 있기 때문입니다. 미국은 지속가능성 프로그램이 클라우드 현대화, 채권 심사 및 기업 보고 요건과 점점 더 밀접하게 연계됨에 따라 계속해서 주요 수요 거점으로 자리 잡고 있습니다. 메이요 클리닉과 마이크로소프트는 2026년 6월, 의료 분야를 위한 최첨단 AI 모델을 개발하기 위한 전략적 제휴를 발표했습니다. 이는 미국의 대규모 의료 시스템과 기술 기업들이 더 엄격한 탄소 배출량 모니터링이 필요한 디지털 워크로드를 어떻게 추진하고 있는지를 여실히 보여줍니다. 따라서 헬스케어용 그린 IT 소프트웨어는 북미에서 다른 대부분의 지역보다 운영 면에서 더 성숙한 단계에 있습니다.
유럽은 헬스케어용 그린 IT 소프트웨어 시장에서 여전히 2위 지역 블록으로서의 지위를 유지하고 있습니다. 이 지역 수요는 의무화된 지속가능성 보고, 조달과 관련된 정보 공개 기대, 그리고 감사 가능한 기업 데이터에 대한 광범위한 압력에 의해 형성되고 있습니다. 대규모 의료 시스템은 파편화된 지속가능성 워크플로우에서 반복 가능한 보고 주기를 지원할 수 있는 공식적인 소프트웨어 환경으로 전환되고 있습니다. Sana Kliniken AG가 2025년에 ESG 데이터 관리를 위해 osapiens를 도입한 사례는 대형 병원 운영 사업자가 이러한 요건을 기업 시스템에 통합하고 있음을 보여줍니다. 이 지역의 구매 경향으로는 새로운 고립된 보고 계층을 생성하지 않으면서 거버넌스, 배출량 산정 및 업무 통합을 결합할 수 있는 플랫폼이 선호되고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 17.85%로 확대될 것으로 예측되며, 헬스케어용 그린 IT 소프트웨어 시장에서 가장 두드러진 성장을 보일 것으로 전망됩니다. 이러한 성장은 공시 요건의 강화, 클라우드를 통한 현대화, 그리고 ESG 보고 수요와 관련된 현지 소프트웨어 개발에 의해 뒷받침되고 있습니다. 후지쯔가 2026년 5월에 AI를 활용한 ESG 공시 분석 서비스를 출시한 것과, 그 이전에 구라시키 중앙병원이 클라우드 전환을 실시한 것은 일본에서 보고 체계와 디지털 인프라의 변화가 동시에 진행되고 있음을 보여줍니다. 남미, 중동 및 아프리카는 현재 시장 규모로 볼 때 아직 작지만, 다국적 의료 그룹이 현지 사업 거점에 기업 차원의 지속가능성 프로그램을 전개함에 따라 도입이 착실히 진행되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.08.07According to Mordor Intelligence, the green IT software for healthcare market size is expected to increase from USD 1.59 billion in 2025 to USD 1.82 billion in 2026 and reach USD 3.95 billion by 2031, growing at a CAGR of 16.76% over 2026-2031.
This report is Segmented by Component (Software and Services), Deployment Mode (Cloud-Based, On-Premise, and Hybrid), Organization Size (Large Enterprises and SMEs), Application (Carbon Footprint, Energy Optimization, ESG Reporting, and IT Infrastructure), End User (Hospitals, Ambulatory, Imaging, Payers, and Life Sciences), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Green IT Software For Healthcare Market Trends and Insights
Rising Energy Cost Pressure Across Healthcare Digital Estates
Rising power use across imaging storage, clinical servers, and connected digital workflows is making the Green IT software for healthcare market more urgent for provider boards. A 2025 study in European Radiology showed that long-term CT data storage consumes significant electricity across storage systems, servers, and network infrastructure, providing hospitals with a clear operating baseline for sustainability action. As digital care expands, energy management and carbon tracking increasingly sit within the same operating workflow rather than in separate teams. That shift favors platforms that can integrate asset selection, workload placement, and reporting outputs into a single system. The immediate effect is a stronger demand for software that can show where energy is consumed and how operational changes can lower both cost and emissions.
Carbon Reporting Requirements Tied To Health System Procurement
Procurement rules are moving the Green IT software for the healthcare market from optional spending to contract-linked spending. From April 6, 2026, NHS Supply Chain required suppliers to complete the Evergreen Sustainable Supplier Assessment Level 1 and to hold a PPN 006-compliant Carbon Reduction Plan covering Scope 1, Scope 2, and relevant Scope 3 emissions. That requirement matters because it pushes carbon data collection into ordinary vendor qualification, renewal, and tender activity. The Journal of Medical Internet Research also documented that unproven generative AI in UK primary care creates a reporting gap because AI-related emissions are not consistently captured in current disclosures. As procurement standards and disclosure expectations tighten together, platforms that support audit-ready reporting gain a clearer path into healthcare budgets.
Fragmented Sustainability Data Across Clinical And Nonclinical Systems
Fragmented data remains the largest barrier inside the Green IT software for healthcare market because sustainability records are spread across clinical, facilities, procurement, and enterprise software systems. Hospitals often keep energy, asset, and operating data in separate environments, which slows the creation of a consistent emissions baseline. That weak starting point makes reporting more difficult and lengthens platform deployment cycles, especially when organizations want a single view across multiple sites. Sana Kliniken AG's 2025 shift to Osapiens for ESG data management underscores why large operators are formalizing enterprise systems rather than relying on disconnected workflows. Until data models and interfaces become more standardized, the Green IT software for the healthcare market will face slower adoption across multisite providers and mid-sized institutions.
Other drivers and restraints analyzed in the detailed report include:
- Cloud Migration Demand For Lower-Emission IT Operations
- Need For Sustainable AI And Data Center Workloads In Healthcare
- Weak Green IT ROI Benchmarking For Mid-Sized Providers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software held 58% of the market in 2025, while services are projected to grow at an 18.12% CAGR through 2031. Software remained the structural anchor because healthcare buyers need a documented and continuously updated platform rather than a one-time consulting exercise. That position is reinforced by disclosure requirements that demand repeatable data collection, audit support, and workflow consistency across reporting periods. In the Green IT software for the healthcare industry, this makes software the base layer that other implementation and advisory services sit around.
Services are still set for the fastest expansion because integration, configuration, validation, and reporting support remain essential for many buyers in the Green IT software for healthcare market. As disclosure scope widens to include supply chain data, AI-related emissions, and multi-framework reporting, organizations need more help turning software outputs into usable compliance records. SAP announced in May 2026 that its new sustainability AI agents can cut packaging compliance hours by more than 50% and reduce scenario simulation time from 1 day to 20 minutes, demonstrating how vendors are automating work that previously required deeper service engagement. This pattern suggests services demand will remain strong in the near term, but more of that work will gradually be shaped by automation.
Cloud-based deployment captured 64% of the Green IT software for healthcare market size in 2025, while hybrid deployment is projected to grow at a 17.50% CAGR through 2031. Cloud remained the largest mode because it aligns with the push to move sustainability analytics away from energy-intensive local infrastructure. Hybrid is growing faster because many healthcare organizations still need local connections to clinical systems, building controls, and sensitive data environments. In the Green IT software for healthcare market, durable demand is created for architectures that combine central reporting tools with controlled local data access.
On-premises deployment is losing relative weight, but it still has a role where strict latency, privacy, and internal control requirements remain. Kurashiki Central Hospital's March 2025 move to the Nutanix Cloud Platform demonstrated how healthcare providers can modernize core systems while supporting broader IT sustainability goals. The practical effect is that buyers are not choosing between legacy and cloud in a simple way, because many are moving through staged transition models instead. The Green IT software for the healthcare market, therefore, favors vendors that can support mixed environments without disrupting existing clinical operations.
Complete Report Scope:
- By Component
- Software
- Services
- By Deployment Mode
- Cloud-Based
- On-Premise
- Hybrid
- By Organization Size
- Large Enterprises
- Small and Medium-Sized Enterprises
- By Application
- Carbon Footprint Management
- Energy and Resource Optimization
- ESG Reporting and Regulatory Compliance
- IT Infrastructure Sustainability Management
- By End User
- Hospitals
- Ambulatory Care Centers
- Diagnostic and Imaging Centers
- Healthcare Payers
- Life Sciences Organizations
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East
- United Arab Emirates
- Saudi Arabia
- Rest of Middle East
- Africa
- South Africa
- Kenya
- Rest of Africa
- North America
Geography Analysis
North America accounted for 38% of the Green IT software market share in the healthcare market in 2025. The region led because it combines a strong base of enterprise software vendors, large integrated health systems, and mature digital infrastructure. The United States remained the core demand center because sustainability programs increasingly intersect with cloud modernization, bond scrutiny, and enterprise reporting needs. Mayo Clinic and Microsoft announced a strategic collaboration in June 2026 to develop a frontier AI model for healthcare, underscoring how large U.S. care systems and technology firms are advancing digital workloads that require stronger carbon oversight. The Green IT software for the healthcare market is therefore more operationally mature in North America than in most other regions.
Europe remained the second-largest regional bloc in the Green IT software for healthcare market. Demand in the region is being shaped by mandatory sustainability reporting, procurement-linked disclosure expectations, and wider pressure for auditable enterprise data. Large health systems are moving from fragmented sustainability workflows to formal software environments that can support repeatable reporting cycles. Sana Kliniken AG's 2025 adoption of osapiens for ESG data management showed how major hospital operators are putting these requirements into enterprise systems. The region's buying pattern favors platforms that can combine governance, emissions accounting, and operational integration without creating another disconnected reporting layer.
Asia-Pacific is projected to expand at a 17.85% CAGR through 2031, making it the fastest-growing region in the Green IT software for healthcare market. Growth is being supported by rising disclosure expectations, cloud modernization, and local software development linked to ESG reporting needs. Fujitsu's May 2026 launch of an AI-powered ESG disclosure analysis service and Kurashiki Central Hospital's earlier cloud migration illustrate how reporting and digital infrastructure changes are advancing at the same time in Japan. South America, the Middle East, and Africa remain smaller in current value, but adoption is still moving forward where multinational healthcare groups extend enterprise sustainability programs across local operations.
- Watershed, Inc.
- Persefoni AI, Inc.
- Sweep SAS
- Normative AB
- Plan A Earth GmbH
- Greenly SAS
- Emitwise Limited
- Measurabl, Inc.
- Sinai Technologies, Inc.
- Dcycle, S.L.
- osapiens Holding GmbH
- Sphera Solutions, Inc.
- Benchmark Gensuite LLC
- Novisto Inc.
- Cority Software Inc.
- FigBytes Inc.
- IBM Corporation
- Salesforce, Inc.
- Microsoft Corporation
- SAP SE
- Schneider Electric SE
- Johnson Controls International plc
- Siemens AG
- Honeywell International Inc.
- Oracle Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Energy Cost Pressure Across Healthcare Digital Estates
- 4.2.2 Carbon Reporting Requirements Tied to Health System Procurement
- 4.2.3 Cloud Migration Demand for Lower-Emission IT Operations
- 4.2.4 Need for Sustainable AI and Data Center Workloads in Healthcare
- 4.2.5 Hospital ESG Budget Linking IT Efficiency to Clinical Resilience
- 4.2.6 Growing Preference for Audit-Ready Sustainability Analytics
- 4.3 Market Restraints
- 4.3.1 Fragmented Sustainability Data Across Clinical and Nonclinical Systems
- 4.3.2 Weak Green IT ROI Benchmarking for Mid-Sized Providers
- 4.3.3 Cybersecurity and Privacy Controls Raising Implementation Complexity
- 4.3.4 Integration Difficulty With Legacy EMR and Facility Systems
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Software
- 5.1.2 Services
- 5.2 By Deployment Mode
- 5.2.1 Cloud-Based
- 5.2.2 On-Premise
- 5.2.3 Hybrid
- 5.3 By Organization Size
- 5.3.1 Large Enterprises
- 5.3.2 Small and Medium-Sized Enterprises
- 5.4 By Application
- 5.4.1 Carbon Footprint Management
- 5.4.2 Energy and Resource Optimization
- 5.4.3 ESG Reporting and Regulatory Compliance
- 5.4.4 IT Infrastructure Sustainability Management
- 5.5 By End User
- 5.5.1 Hospitals
- 5.5.2 Ambulatory Care Centers
- 5.5.3 Diagnostic and Imaging Centers
- 5.5.4 Healthcare Payers
- 5.5.5 Life Sciences Organizations
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 United Kingdom
- 5.6.3.2 Germany
- 5.6.3.3 France
- 5.6.3.4 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Australia
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East
- 5.6.5.1 United Arab Emirates
- 5.6.5.2 Saudi Arabia
- 5.6.5.3 Rest of Middle East
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 Kenya
- 5.6.6.3 Rest of Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Watershed, Inc.
- 6.4.2 Persefoni AI, Inc.
- 6.4.3 Sweep SAS
- 6.4.4 Normative AB
- 6.4.5 Plan A Earth GmbH
- 6.4.6 Greenly SAS
- 6.4.7 Emitwise Limited
- 6.4.8 Measurabl, Inc.
- 6.4.9 Sinai Technologies, Inc.
- 6.4.10 Dcycle, S.L.
- 6.4.11 osapiens Holding GmbH
- 6.4.12 Sphera Solutions, Inc.
- 6.4.13 Benchmark Gensuite LLC
- 6.4.14 Novisto Inc.
- 6.4.15 Cority Software Inc.
- 6.4.16 FigBytes Inc.
- 6.4.17 IBM Corporation
- 6.4.18 Salesforce, Inc.
- 6.4.19 Microsoft Corporation
- 6.4.20 SAP SE
- 6.4.21 Schneider Electric SE
- 6.4.22 Johnson Controls International plc
- 6.4.23 Siemens AG
- 6.4.24 Honeywell International Inc.
- 6.4.25 Oracle Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment