|
시장보고서
상품코드
2119792
태국의 데이터센터 건설 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Thailand Data Center Construction - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
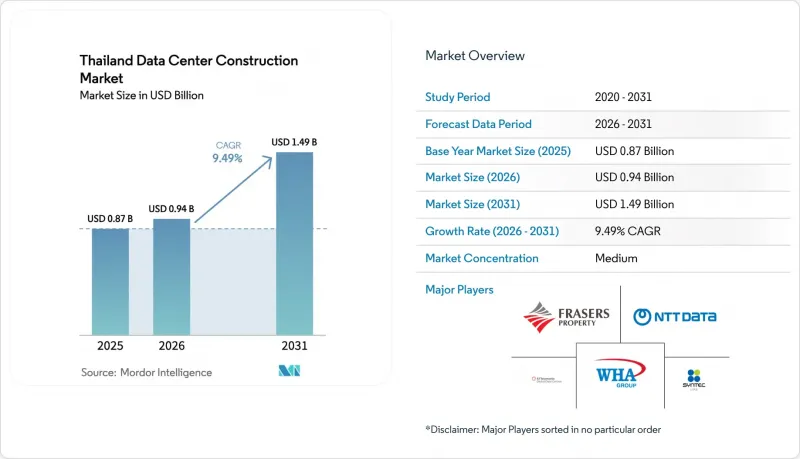
에 의하면, 태국의 데이터센터 건설 시장 규모는 2025년 8억 7,000만 달러로 평가되었습니다. 2026년에는 9억 4,000만 달러로 확대되어 2031년까지 14억 9,000만 달러에 이르고 2026-2031년에 걸쳐 CAGR 9.49%를 나타낼 것으로 예측됩니다.
본 보고서는 티어 유형(Tier 1·2, Tier 3, 티어 4), 데이터센터 규모(소규모, 중규모, 대규모, 하이퍼스케일),데이터센터 유형(코로케이션 데이터센터, 하이퍼스케일러·클라우드 서비스 제공업체, 엔터프라이즈·엣지 데이터센터), 인프라(전기 인프라, 기계 인프라, 기타)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
태국의 데이터센터 건설 시장 동향 및 인사이트
하이퍼스케일러에 의한 클라우드 서비스 구축 확대
Amazon Web Services, Google Cloud, Microsoft Azure가 소버린 클라우드 및 재생에너지 요건을 충족해야 하는 현지 지역으로의 진출을 추진함에 따라, 수십억 달러 규모의 자체 인프라 구축 열풍이 태국의 데이터센터 건설 시장을 재편하고 있습니다. 투자위원회는 2025년 3월, 베이징 하오얀(Beijing Haoyang)이 라용(Rayong) 주에 건설하는 300MW 캠퍼스 등 총 27억 달러 규모의 신규 데이터센터 프로젝트를 승인하며, 하이퍼스케일러를 주요 임차인으로 하는 프로젝트의 파급 효과를 입증했습니다. 촌부리와 라용은 이용 가능한 토지가 풍부하고, 해저 케이블 상륙 지점과 인접해 있으며, 계통 전력 요금을 10-15% 인하하는 직접 전력 구매 시범 사업 덕분에 핵심 거점으로 부상했습니다. 각 하이퍼스케일러 기업들이 AI 훈련을 위해 랙당 100kW의 밀도를 선호함에 따라, 이에 따른 액체 냉각 도입도 가속화되고 있습니다. 일등지의 부지가 매진됨에 따라, 메가와트 규모의 부지를 둘러싼 경쟁은 현재 EEC(동부 경제 회랑)의 2차 부지까지 파급되고 있습니다.
동부 경제 회랑(EEC)의 디지털 회랑에 대한 정부의 우대 조치
15년간의 면세 조치, IT 장비의 무세 수입, 토지 소유권 절차 간소화가 EEC 정책 패키지의 기반을 이루고 있으며, 이는 그동안 개발업자들을 인근 말레이시아나 베트남으로 몰아내던 재정적 부담의 상당 부분을 해소하고 있습니다. ‘디지털 파크 태국(Digital Park Thailand)’은 해저 케이블 시스템에 다크 파이버를 공급하며, 요건을 충족하는 데이터센터가 상업용 요금보다 낮은 가격으로 최대 50MW의 재생에너지를 조달할 수 있도록 하고 있습니다. ‘FastPass’ 프레임워크를 통해 인허가 취득 기간이 18개월에서 6개월로 단축됩니다. 이는 토목·전기·기계 공사를 병행하여 진행하는 하이퍼스케일 건설에 있어 매우 중요한 이점입니다. WHA 코퍼레이션은 2025년 1분기에 단일 데이터센터 고객에게 180에이커의 토지를 매각했다고 밝혔으며, 이는 EEC 구역에 대한 수요가 지속되고 있음을 뒷받침합니다. 이러한 우대 조치를 종합하면, 예측 연평균 성장률(CAGR)에 2% 이상의 상승 효과를 가져옵니다.
지역 내 타국과 비교한 전력 요금의 프리미엄
2025년 상업용 전기 요금은 1kWh당 평균 4.20바트로, 말레이시아나 베트남보다 약 15-20% 더 높아, 지속적으로 높은 부하를 소비하는 GPU 클러스터의 총 소유 비용(TCO)을 상승시켰습니다. EGAT의 직접 전력 구매 시범 프로그램에서는 조건을 충족하는 시설이 재생에너지를 할인된 가격에 확보할 수 있지만, 이 2GW 규모의 프로그램이 지원하는 대상은 40곳 이하의 대규모 사이트로 제한되어 있어 하이퍼스케일러에게 유리하게 작용하며, 중견 코로케이션 기업에는 표준 요금이 적용될 것입니다. 개발사들은 현재 피크 수요를 줄이기 위해 부지 내 태양광 발전과 축전지를 결합한 시스템 도입을 검토하고 있지만, 설비 투자(CAPEX)로 인해 투자 회수 위험이 높아지고 있습니다. 2024년 전력 개발 계획에 제시된 10GW 규모의 재생에너지 확대가 가속화되지 않는 한, 높은 전기 요금이 소규모 건설을 억제할 가능성이 있습니다.
부문 분석
2025년 태국의 데이터센터 건설 시장의 56.43%를 차지한 것은 Tier 3 시설로, 티어 4와 같은 고비용의 내결함성을 필요로 하지 않으면서 기업에 99.982%의 서비스 수준 계약(SLA)을 제공합니다. 그러나 하이퍼스케일러 기업들은 랙당 30kW를 초과하는 밀도로 AI 훈련 모델을 호스팅하기 위해 N+N 방식의 전원 및 냉각을 요구하고 있으며, 이로 인해 티어 4 시설 건설이 연평균 성장률(CAGR) 10.32%로 확대되고 있습니다. SUPERNAP Thailand의 티어 IV 촌부리 캠퍼스는 2024년에 동남아시아에서도 몇 안 되는 내결함성 사이트 중 하나가 되어, 사업자들에게 GPU 지원 설계 청사진을 제공했습니다. 2025년 4월 STT GDC가 도입한 랙당 100kW 시스템과 같은 수냉식 개조는 전력 사용 효율(PUE)을 1.6에서 1.2로 향상시킴으로써 티어 4의 경제성을 더욱 높이고 있습니다.
한때 중소기업 사이에서 인기가 높았던 Tier 1 및 Tier 2 데이터센터는 워크로드가 더 높은 티어의 코로케이션 스위트로 집중됨에 따라 감소 추세를 보이고 있습니다. Tier 3으로의 업그레이드 자금을 조달하지 못하는 사업자는 인수되거나 시장에서 철수할 수밖에 없게 됩니다. 티어 4로의 투자 전환으로 인해 기계적 복잡성이 증가함에 따라, 업타임 인스티튜트의 프로토콜에 따라 내결함성을 인증할 수 있는 전문 엔지니어링 기업과의 제휴가 촉진될 것입니다. 예측 기간 동안 태국의 데이터센터 건설 시장 규모의 기반은 여전히 Tier 3이 담당하겠지만, AI 도입이 가속화됨에 따라 티어 4는 다른 모든 티어를 능가하는 성장률을 보일 것으로 예측됩니다.
2025년 투자액의 54.54%는 대규모 시설(10-50MW)이 차지했지만, 50MW를 초과하는 캠퍼스로 정의되는 하이퍼스케일 부문은 연평균 성장률(CAGR) 10.64%로 확대되고 있습니다. 아마존 웹 서비스(AWS)와 구글 클라우드는 각각 하이퍼스케일 지역을 위해 10억 달러가 넘는 다년간의 투자를 계획하고 있는 반면, 베이징 하오양사의 300MW 라용 프로젝트는 완공될 경우 태국 내 기존 시설을 훨씬 능가하게 될 것입니다. 발표된 용량이 모두 실현된다면, 태국의 데이터센터 건설 시장에서 하이퍼스케일 프로젝트 시장 규모는 2029년까지 대형 코로케이션 시설을 능가할 전망입니다. 슈나이더 일렉트릭의 모듈식 건설 및 조립식 전원실을 통해 개발사는 도입 주기를 6개월 단축할 수 있습니다. 이는 주요 임차인이 24개월 이내의 ‘퍼스트 트랙’ 납품을 요구할 경우 경쟁 우위를 점할 수 있게 해줍니다.
중규모(5-10MW) 시설은 기업들이 퍼블릭 클라우드로 직접 전환하거나 워크로드를 공유형 20MW 코로케이션 홀로 통합하는 경향이 있어 뒤처지고 있습니다. 소규모(5MW 이하) 시설은 현재 엣지 컴퓨팅과 재해 복구에 중점을 두고 있으며, 특히 치앙마이와 푸켓에서는 지역적인 고객 기반이 있어 로컬 캐시가 정당화되고 있습니다. 그럼에도 불구하고 태국의 데이터센터 건설 시장에는 5G 기지국 및 소매 거점과 연계된 마이크로 시설에 대한 수요가 여전히 존재하여 공급망의 다양성을 유지하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.10According to Mordor Intelligence, the Thailand data center construction market size is expected to increase from USD 0.87 billion in 2025 to USD 0.94 billion in 2026 and reach USD 1.49 billion by 2031, growing at a CAGR of 9.49% over 2026-2031.
This report is Segmented by Tier Type (Tier 1 and 2, Tier 3, and Tier 4), Data Center Size (Small, Medium, Large, and Hyperscale), Data Center Type (Colocation Data Center, Hyperscalers/Cloud Service Provider, and Enterprise and Edge Data Center), and Infrastructure (Electrical Infrastructure, Mechanical Infrastructure, and More). The Market Forecasts are Provided in Terms of Value (USD).
Thailand Data Center Construction Market Trends and Insights
Intensified Cloud-Service Build-Outs by Hyperscalers
A multibillion-dollar wave of captive infrastructure is reshaping the Thailand data center construction market as Amazon Web Services, Google Cloud, and Microsoft Azure commit to local regions that must meet sovereign-cloud and renewable-energy mandates. The Board of Investment approved USD 2.7 billion in new data center projects in March 2025, including a 300 MW campus in Rayong by Beijing Haoyang, confirming the pull-through effect of hyperscaler anchor tenants. Chonburi and Rayong have emerged as core nodes thanks to land availability, proximity to submarine-cable landing sites, and direct power-purchase pilots that shave 10-15% off grid tariffs. Liquid-cooling adoption is quickening in tandem because hyperscalers favor 100 kW-per-rack densities for AI training. Competition for megawatt-scale sites is now spilling into secondary EEC plots as prime parcels sell out.
Government Incentives for Eastern Economic Corridor Digital Corridors
Fifteen-year tax holidays, duty-free imports of IT equipment, and streamlined land-ownership rights underpin the EEC policy package, removing much of the fiscal drag that historically pushed developers into neighboring Malaysia or Vietnam. Digital Park Thailand supplies dark fiber to submarine cable systems and enables qualifying data centers to procure up to 50 MW of renewable power at rates below commercial tariffs. The FastPass framework compresses permitting from eighteen to six months, a critical advantage for hyperscale builds that stage civil, electrical, and mechanical work concurrently. WHA Corporation disclosed land sales of 180 acres to a single data-center customer in 1Q 2025, underscoring sustained appetite for EEC plots. Collectively, these incentives add more than two percentage points to forecast CAGR.
Premium Electricity Tariffs versus Regional Peers
Commercial tariffs averaged THB 4.20 per kWh in 2025, roughly 15-20% higher than Malaysia or Vietnam, driving up total cost of ownership for GPU clusters that draw continuous high loads. EGAT's direct power-purchase pilot lets qualifying facilities lock in renewable energy at discounts, but the 2 GW program supports fewer than forty large sites, advantaging hyperscalers and leaving mid-tier colocation firms on standard rates. Developers are now exploring on-site solar-plus-battery systems to shave peak demand, though capex adds payback risk. Unless the 2024 Power Development Plan's 10 GW renewable expansion is accelerated, high tariffs may curb small-format builds.
Other drivers and restraints analyzed in the detailed report include:
- Growth in OTT Video Traffic and Edge-Node Demand
- Mandatory Data-Sovereignty Compliance (PDPA)
- Lengthy 115 kV Grid-Connection Approval Cycles
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Tier 3 installations controlled 56.43% of Thailand data center construction market in 2025, offering enterprises 99.982% service-level agreements without Tier 4's costlier fault tolerance. Hyperscalers, however, are driving a 10.32% CAGR in Tier 4 builds by insisting on N + N power and cooling to host AI training models at densities that breach 30 kW per rack. SUPERNAP Thailand's Tier IV Chonburi campus became one of Southeast Asia's only fault-tolerant sites in 2024, giving operators a blueprint for GPU-ready design. Liquid-cooling retrofits such as the 100 kW-per-rack system deployed by STT GDC in April 2025 further bolster Tier 4 economics by boosting power-usage effectiveness from 1.6 to 1.2.
Tier 1 and Tier 2 footprints, once popular with small enterprises, are declining as workloads consolidate into higher-tier colocation suites. Operators that cannot finance Tier 3 upgrades face acquisition or exit. The investment tilt toward Tier 4 elevates mechanical complexity, encouraging partnership with specialist engineering firms that can certify fault tolerance under Uptime Institute protocols. Over the forecast window, Tier 3 will still anchor the Thailand data center construction market size, but Tier 4 is set to outgrow every other tier as AI adoption accelerates.
Large-format facilities (10-50 MW) represented 54.54% of 2025 spending, yet the hyperscale segment, defined as campuses topping 50 MW, is moving at a 10.64% CAGR. Amazon Web Services and Google Cloud have each earmarked multiyear investments exceeding USD 1 billion for hyperscale regions, while Beijing Haoyang's 300 MW Rayong plan will dwarf existing Thai footprints once completed. The Thailand data center construction market size for hyperscale projects is set to overtake large-format colocation by 2029 if all announced capacity materializes. Modular construction and prefabricated power rooms from Schneider Electric let developers shave deployment cycles by 6 months, a competitive edge when anchor tenants require first-rack delivery within 24 months.
Medium-format (5-10 MW) facilities lag because enterprises either leapfrog directly into public cloud or consolidate workloads into shared 20 MW colocation halls. Small (sub-5 MW) sites now skew toward edge computing and disaster recovery, particularly in Chiang Mai and Phuket, where regional consumer bases justify local caching. Nonetheless, the Thailand data center construction market retains a place for micro-facilities tied to 5G towers and retail hubs, keeping supply chains diverse.
Complete Report Scope:
- By Tier Type
- Tier 1 and 2
- Tier 3
- Tier 4
- By Data Center Size
- Small
- Medium
- Large
- Hyperscale
- By Data Center Type
- Colocation Data Center
- Hyperscalers/Cloud Service Provider (CSPs)
- Enterprise and Edge Data Center
- By Infrastructure
- Electrical Infrastructure
- Power Distribution Solution
- Power Backup Solutions
- Mechanical Infrastructure
- Cooling Systems
- Racks and Cabinets
- Servers and Storage
- Other Mechanical Infrastructure
- General Construction
- Services - Design and Consulting, Integration, Support and Maintenance
- Electrical Infrastructure
List of Companies Covered in this Report:
- Aurecon Group Pty Ltd
- AECOM (Thailand) Ltd
- Princeton Digital Group
- Syntec Construction PCL
- Central Pattana PCL
- Thai Kajima Co., Ltd
- Thai Obayashi Corp. Ltd
- PPS Group PCL
- Frasers Property (Thailand) PCL
- WHA Corporation PCL
- STT GDC Thailand Co., Ltd
- NTT Global Data Centers (Thailand) Ltd
- True Internet Data Center Co., Ltd
- SUPERNAP (Thailand) Co., Ltd
- CAT Telecom PLC (National Telecom)
- GULF INNO Infrastructure Co., Ltd
- Huawei Technologies (Thailand) Co., Ltd
- Schneider Electric (Thailand) Ltd
- Delta Electronics (Thailand) PCL
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Intensified Cloud-Service Build-Outs by Hyperscalers
- 4.2.2 Government Incentives for Eastern Economic Corridor Digital Corridors
- 4.2.3 Growth in OTT Video Traffic and Edge-Node Demand
- 4.2.4 Accelerating Liquidity in REIT-Backed Data-Center Real-Estate
- 4.2.5 Mandatory Data-Sovereignty Compliance (PDPA)
- 4.2.6 Emerging Quantum-Ready Power and Cooling Standards
- 4.3 Market Restraints
- 4.3.1 Premium Electricity Tariffs versus Regional Peers
- 4.3.2 Lengthy 115 kV Grid-Connection Approval Cycles
- 4.3.3 Rising Land Prices in Metro Bangkok
- 4.3.4 Shortage of Uptime-Tier-Accredited Engineers
- 4.4 Industry Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Key Data Center Statistics
- 4.8.1 Exhaustive Data Center Operators in Thailand (in MW)
- 4.8.2 List of Major Upcoming Data Center Projects in Thailand (2025-2030)
- 4.8.3 CAPEX and OPEX For Thailand Data Center Construction
- 4.8.4 Data Center Power Capacity Absorption In MW, Thailand, 2023 and 2024
- 4.9 Artificial Intelligence (AI) Inclusion in Data Center Construction in Thailand
- 4.10 Regulatory and Compliance Framework
- 4.11 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Tier Type
- 5.1.1 Tier 1 and 2
- 5.1.2 Tier 3
- 5.1.3 Tier 4
- 5.2 By Data Center Size
- 5.2.1 Small
- 5.2.2 Medium
- 5.2.3 Large
- 5.2.4 Hyperscale
- 5.3 By Data Center Type
- 5.3.1 Colocation Data Center
- 5.3.2 Hyperscalers/Cloud Service Provider (CSPs)
- 5.3.3 Enterprise and Edge Data Center
- 5.4 By Infrastructure
- 5.4.1 Electrical Infrastructure
- 5.4.1.1 Power Distribution Solution
- 5.4.1.2 Power Backup Solutions
- 5.4.2 Mechanical Infrastructure
- 5.4.2.1 Cooling Systems
- 5.4.2.2 Racks and Cabinets
- 5.4.2.3 Servers and Storage
- 5.4.2.4 Other Mechanical Infrastructure
- 5.4.3 General Construction
- 5.4.4 Services - Design and Consulting, Integration, Support and Maintenance
- 5.4.1 Electrical Infrastructure
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Data Center Infrastructure Investment Based on Megawatt (MW) Capacity, 2024 vs 2030
- 6.5 Data Center Construction Landscape (Key Vendors Listings)
- 6.6 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.6.1 Aurecon Group Pty Ltd
- 6.6.2 AECOM (Thailand) Ltd
- 6.6.3 Princeton Digital Group
- 6.6.4 Syntec Construction PCL
- 6.6.5 Central Pattana PCL
- 6.6.6 Thai Kajima Co., Ltd
- 6.6.7 Thai Obayashi Corp. Ltd
- 6.6.8 PPS Group PCL
- 6.6.9 Frasers Property (Thailand) PCL
- 6.6.10 WHA Corporation PCL
- 6.6.11 STT GDC Thailand Co., Ltd
- 6.6.12 NTT Global Data Centers (Thailand) Ltd
- 6.6.13 True Internet Data Center Co., Ltd
- 6.6.14 SUPERNAP (Thailand) Co., Ltd
- 6.6.15 CAT Telecom PLC (National Telecom)
- 6.6.16 GULF INNO Infrastructure Co., Ltd
- 6.6.17 Huawei Technologies (Thailand) Co., Ltd
- 6.6.18 Schneider Electric (Thailand) Ltd
- 6.6.19 Delta Electronics (Thailand) PCL
- 6.7 List of Data Center Construction Companies
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment