

|
시장보고서
상품코드
2116368
프랑스의 자동차 엔진오일 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)France Automotive Engine Oils - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 프랑스 자동차 엔진오일 시장 규모는 2025년 2억 1,690만 리터에서 2026년에는 2억 1,293만 리터로 축소해, 2026년부터 2031년까지 CAGR -1.83%로 성장을 지속하여, 2031년에는 1억 9,415만 리터에 이를 것으로 예측됩니다.
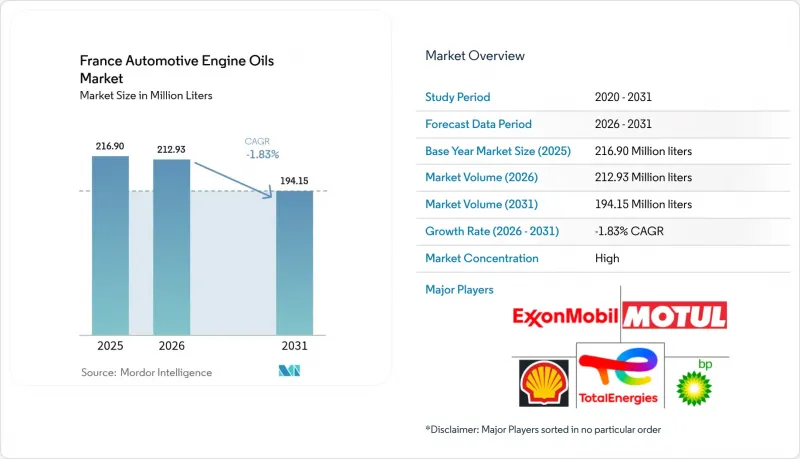
본 보고서는 제품 유형(승용차용 엔진오일(0W-XX, 5W-XX, 10W-XX, 15W-XX, 모노그레이드, 기타 등급),대형차용 엔진오일(0W-XX, 5W-XX, 10W-XX, 15W-XX, 모노그레이드 및 기타 등급), 오토바이용 엔진오일(0W-XX, 5W-XX, 10W-XX 등)),기유(광유, 합성유, 반합성유 및 바이오)별로 분류되어 있습니다. 시장 전망은 판매량(리터)으로 표시되어 있습니다.
프랑스 자동차 엔진오일 시장 동향 및 인사이트
차량의 노후화로 인해 정비 수요가 장기화되고 있습니다.
프랑스 승용차의 평균 수명은 11.5년이며, 가솔린 및 디젤 엔진의 대부분이 일반적인 OEM 보증 기간을 훨씬 초과한 후에도 계속 운행되고 있습니다. 전체 차량의 거의 절반이 8-15년 범위에 속하며, 이 주행 거리 대에서는 일반적으로 적어도 1년에 한 번 오일 교환이 필요합니다. 지방이나 도시 근교 운전자들은 공공 충전 인프라가 제한적이고 가처분 소득도 낮기 때문에 내연기관 차량을 더 오래 보유하는 경향이 있어, 이에 따라 광물유 및 반합성 PCMO에 대한 베이스로드 수요가 유지되고 있습니다. 차량 보유 기간의 장기화는 구형 엔진용으로 설계된 점도 등급에 대한 수요도 뒷받침하고 있으며, ACEA 2024 규격에서는 산화 안정성 기준치가 상향 조정되어 프리미엄 합성유가 유리해졌습니다. 그 결과, 총 판매량은 감소 추세를 보이고 있으나, 시장에서는 여전히 예측 가능한 정비 주기가 유지되고 있어, 이것이 전기차로의 급속한 전환을 부분적으로 완화하고 있습니다.
OEM 주도의 저점도 합성유로의 전환(유로 6/7)
유로 7에서는 2025년 이후 신차 모델에 대해 실제 주행 배기가스 규제 준수가 요구되며, 공장 충전 기준은 0W-20, 디젤 승용차 용도의 경우 5W-30의 ACEA C5 또는 C6 카테고리로 전환되고 있습니다. 스텔란티스 산하의 프랑스계 OEM 각사는 이미 많은 신형 가솔린 차량 모델의 오일 주입을 저점도 오일로 전환하고 있으며, 이러한 동향은 딜러 및 퀵 서비스 채널을 통해 애프터마켓에도 반영되고 있습니다. 이러한 새로운 규격을 충족하는 합성유는 20,000-30,000km라는 연장된 교환 주기를 실현하며, 오일 판매업체는 프리미엄 포지셔닝을 통해 판매 단가 하락을 상쇄할 수 있게 됩니다. ATIEL의 ‘행동 강령’은 제품 승인을 엄격한 품질 감사와 연계하고 있어, 기존 블렌딩 업체에 유리한 높은 진입 장벽을 형성하고 있습니다. 중기적으로는 저점도 오일의 보급으로 인해 프랑스 자동차 엔진오일 시장에서 합성 오일의 점유율이 확대될 것으로 예측됩니다.
전기차(EV)의 보급 확대가 내연기관용 오일 판매량을 감소시킨다.
배터리식 전기차(BEV)의 신규 등록 대수는 증가하고 있으며, 정부 정책상 2030년까지 시장 침투율 66%를 목표로 하고 있습니다. 파리, 리옹,마르세유를 아우르는 도시 지역의 저배출 구역(ZFE)에서는 이미 구형 디젤 차량에 대해 통행 제한이 부과되고 있어, 내연기관 차량(VEHICLES)의 폐차가 가속화되고 있습니다. 판매량 감소는 카셰어링 및 라스트 마일 배송 분야에서 특히 두드러집니다. 이러한 분야는 총 주행 거리가 긴 반면, 총 소유 비용(TCO) 절감을 위해 전기차로의 전환이 가장 빠르게 진행되고 있습니다. 국도변 충전 인프라가 정비됨에 따라 중형 상용차의 도입이 가속화되고 있으며, 이는 대형 엔진오일 시장에 2차적인 영향을 미치고 있습니다.
부문 분석
2025년, 프랑스 자동차 엔진오일 시장에서 승용차용 엔진오일은 시장 점유율의 62.05%를 차지했습니다. 그러나 도시 지역에서 전기차 보급이 가속화됨에 따라, 이 부문은 절대적인 판매량 감소 폭이 가장 큽니다. 대형차용 엔진오일은 하이브리드차 및 소형 상용차의 도입이 증가하고 있음에도 불구하고, 비교적 완만한 축소 추세를 보이고 있습니다. 장거리 트럭 운송의 경우, 수소 및 대용량 충전을 위한 인프라가 정비될 때까지는 디젤 구동이 유지되고 있습니다. 오토바이용 엔진오일은 레저로서의 라이딩 문화와 이륜차 전동화에 대한 규제 시급성이 낮아 완화된 영향으로 연평균 성장률(CAGR)이 -1.64%에 그치며 가장 견조한 추세를 보이고 있습니다. PCMO(승용차용 엔진오일) 시장에서는 유로 7 규제의 도입이 다가옴에 따라 0W-30 및 5W-30 합성 오일이 시장 점유율을 확대하고 있어, 기존의 10W-40 광물유 판매량을 압박하고 있습니다. 커넥티드카의 데이터 플랫폼은 오일 교환 알림을 점점 더 개별적으로 최적화하고 있으며, 소비자의 행동을 ‘달력에 기반한 정기적인 정비’에서 ‘필요할 때 서비스를 받는’ 방향으로 유도함으로써, 단거리 소매점의 고객 유치 패턴을 재구성하고 있습니다.
PCMO의 우위가 지속되고 있는 배경에는 중고차의 전기화에 관한 정책 지연도 있습니다. 남유럽 인접 국가들로부터 내연기관(ICE)이 탑재된 중고차가 지방 딜러들에게 공급되면서, 여전히 중SAP 블렌드에 의존하고 있는 구형 엔진의 수명을 연장시키고 있습니다. 그러나 2020년대 후반에 BEV의 가격이 진정으로 동 수준에 도달하면, 애널리스트들은 PCMO 수요가 더욱 급감할 것으로 예측하고 있으며, 공급업체들은 수익을 안정시키기 위해 변속기 오일, EV용 냉각수 및 보조 구동계 윤활유로 다각화할 수밖에 없을 것입니다. 합성 PCMO의 프리미엄화는 이러한 타격을 완화하고, 판매량이 감소하고 있음에도 불구하고 단위당 수익을 끌어올리고 있습니다. 이러한 대응책은 지속가능성 지표를 충족하기 위해 재생 기유를 접목한 토탈에너지즈의 ‘Rubia’ 및 ‘Quartz EV3R’ 시리즈에서 확인할 수 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
제8장 CEO가 생각해야 할 중요 전략적 과제
JHS 26.08.28According to Mordor Intelligence, the France automotive engine oils market size is expected to grow from 216.90 million liters in 2025 to 212.93 million liters in 2026 and is forecast to reach 194.15 million liters by 2031 at -1.83% CAGR over 2026-2031.
This report is Segmented by Product Type (Passenger Car Motor Oil (0W-XX, 5W-XX, 10W-XX, 15W-XX, Monogrades, and Other Grades), Heavy Duty Motor Oil (0W-XX, 5W-XX, 10W-XX, 15W-XX, Monogrades, and Other Grades), and Motorcycle Engine Oil (0W-XX, 5W-XX, 10W-XX, and More)), Base Stock (Mineral, Synthetic, Semi-Synthetic, and Bio-Based). Market Forecasts are Provided in Terms of Volume (Litres).
France Automotive Engine Oils Market Trends and Insights
Ageing Vehicle Parc Prolongs Maintenance Demand
France's passenger cars have an average service life of 11.5 years, keeping a large share of petrol and diesel engines on the road well past the typical OEM warranty window. Nearly half the fleet falls within the 8-15-year band, a mileage bracket that typically requires at least one oil change per year. Rural and peri-urban drivers tend to retain ICE vehicles longer due to limited public charging infrastructure and lower disposable income, thereby sustaining base-load demand for mineral and semi-synthetic PCMO. Extended vehicle ownership also fuels demand for viscosity grades engineered for older engines, with the ACEA 2024 sequences introducing higher oxidative stability thresholds that favor premium synthetics. Consequently, while overall liters ebb, the market still records predictable maintenance cycles that partially buffer rapid EV substitution.
OEM-Driven Low-Viscosity Synthetic Shift (Euro 6/7)
Euro 7 brings real-driving-emission compliance from 2025 for new vehicle types, pushing factory-fill standards toward 0W-20 and, in diesel passenger applications, 5W-30 ACEA C5 or C6 categories. French OEMs under the Stellantis umbrella have already transitioned many of their new gasoline models to low-viscosity fill, a trend mirrored in the aftermarket through dealer and quick-service channels. Synthetic oils meeting these newer sequences deliver extended intervals of 20,000-30,000 km, enabling oil marketers to offset lower units with premium positioning. ATIEL's Code of Practice ties product approvals to rigorous quality audits, fostering a high barrier to entry that favors established blenders. Over the medium term, low-viscosity uptake is forecast to increase the synthetic share of the French automotive engine oils market.
EV Parc Expansion Cutting ICE-Oil Volumes
New registrations of battery-electric vehicles are increasing, and government policy aims for 66% market penetration by 2030. Urban low-emission zones (ZFE) covering Paris, Lyon, and Marseille already impose access restrictions on older diesel models, accelerating ICE scrappage. The volume erosion is particularly acute in ride-sharing and last-mile delivery segments, which collectively log high mileage but adopt EVs the fastest to capture total-cost-of-ownership gains. As charging infrastructure expands along national highways, the adoption of medium-duty commercial vehicles accelerates, creating a second-order drag on heavy-duty engine oils.
Other drivers and restraints analyzed in the detailed report include:
- E-Commerce and Organized After-Sales Channels
- Passenger-Car Oil Resilience Versus Other Lubes
- Long-Drain Synthetic Oils Lower Liter Turnover
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Passenger car motor oil accounted for 62.05% of the France automotive engine oils market share in 2025. The segment nevertheless registers the steepest absolute volume decline as EV uptake accelerates in urban zip codes. Heavy-duty motor oil exhibits a more moderate contraction, despite rising hybrid and light-commercial vehicle adoption. Long-haul trucking retains diesel propulsion pending the development of infrastructure for hydrogen or high-capacity charging. Motorcycle engine oil exhibits the most resilient trajectory, shrinking at only a -1.64% CAGR, cushioned by the recreational riding culture and lower regulatory urgency to electrify two-wheelers. Within PCMO, 0W-30 and 5W-30 synthetics are gaining market share as the Euro 7 implementation nears, squeezing legacy 10W-40 mineral volumes. Connected-vehicle data platforms increasingly tailor oil-change alerts, nudging consumer behavior toward "service when needed," rather than calendar-based routines, thereby reshaping short-chain retail traffic patterns.
Continued PCMO dominance also derives from policy delays on used-car electrification. Second-hand ICE imports from Southern European neighbors supply rural dealerships, extending the lifecycle of older engines that still rely on mid-SAP blends. However, once true pricing parity arrives for BEVs in the late 2020s, analysts expect a sharper PCMO downshift, compelling suppliers to diversify into transmission fluids, EV coolants, and ancillary driveline lubricants to stabilize their revenue. Synthetic PCMO premiumization mitigates the blow, lifting revenue per unit despite contracting volumes, an adaptation visible in TotalEnergies' Rubia and Quartz EV3R ranges, which incorporate regenerated base oil to meet sustainability metrics.
Complete Report Scope:
- By Product Type
- Passenger Car Motor Oil (PCMO)
- 0W-XX
- 5W-XX
- 10W-XX
- 15W-XX
- Monogrades
- Other Grades
- Heavy Duty Motor Oil (HDMO)
- 0W-XX
- 5W-XX
- 10W-XX
- 15W-XX
- Monogrades
- Other Grades
- Motorcycle Engine Oil (MCO)
- 0W-XX
- 5W-XX
- 10W-XX
- 15W-XX
- Monogrades
- Other Grades
- Passenger Car Motor Oil (PCMO)
- By Base Stock
- Mineral
- Synthetic
- Semi-Synthetic
- Bio-Based
List of Companies Covered in this Report:
- BP p.l.c.
- Chevron Corporation
- Eni SpA
- Exxon Mobil Corporation
- FUCHS
- Gulf Oil International Ltd
- IGOL
- Liqui Moly
- Lukoil
- Motul
- PETRONAS Lubricants International
- Shell plc
- SK Enmove co. Ltd
- TotalEnergies
- Wolf Oil Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Ageing vehicle parc prolongs maintenance demand
- 4.2.2 OEM-driven low-viscosity synthetic shift (Euro 6/7)
- 4.2.3 E-commerce and organised after-sales channels
- 4.2.4 Passenger-car oil resilience vs other lubes
- 4.2.5 Connected oil-analysis and smart-tank services
- 4.3 Market Restraints
- 4.3.1 EV parc expansion cutting ICE-oil volumes
- 4.3.2 Long-drain synthetic oils lower litre turnover
- 4.3.3 Counterfeit / private-label dilution in retail
- 4.4 Value Chain and Distribution Channel Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Industry Rivalry
- 4.6 Regulatory Framework
- 4.7 Automotive Industry Trends
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Product Type
- 5.1.1 Passenger Car Motor Oil (PCMO)
- 5.1.1.1 0W-XX
- 5.1.1.2 5W-XX
- 5.1.1.3 10W-XX
- 5.1.1.4 15W-XX
- 5.1.1.5 Monogrades
- 5.1.1.6 Other Grades
- 5.1.2 Heavy Duty Motor Oil (HDMO)
- 5.1.2.1 0W-XX
- 5.1.2.2 5W-XX
- 5.1.2.3 10W-XX
- 5.1.2.4 15W-XX
- 5.1.2.5 Monogrades
- 5.1.2.6 Other Grades
- 5.1.3 Motorcycle Engine Oil (MCO)
- 5.1.3.1 0W-XX
- 5.1.3.2 5W-XX
- 5.1.3.3 10W-XX
- 5.1.3.4 15W-XX
- 5.1.3.5 Monogrades
- 5.1.3.6 Other Grades
- 5.1.1 Passenger Car Motor Oil (PCMO)
- 5.2 By Base Stock
- 5.2.1 Mineral
- 5.2.2 Synthetic
- 5.2.3 Semi-Synthetic
- 5.2.4 Bio-Based
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Production Capacity, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 BP p.l.c.
- 6.4.2 Chevron Corporation
- 6.4.3 Eni SpA
- 6.4.4 Exxon Mobil Corporation
- 6.4.5 FUCHS
- 6.4.6 Gulf Oil International Ltd
- 6.4.7 IGOL
- 6.4.8 Liqui Moly
- 6.4.9 Lukoil
- 6.4.10 Motul
- 6.4.11 PETRONAS Lubricants International
- 6.4.12 Shell plc
- 6.4.13 SK Enmove co. Ltd
- 6.4.14 TotalEnergies
- 6.4.15 Wolf Oil Corporation
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment


