

|
시장보고서
상품코드
2116388
말레이시아의 자동차 엔진오일 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Malaysia Automotive Engine Oils - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 말레이시아 자동차 엔진오일 시장 규모는 2025년에 1억 8,023만 리터로 평가되어 2026년 1억 8,304만 리터에서 2031년까지 1억 9,781만 리터에 이를 것으로 예측되며, 예측 기간 CAGR은 1.56%입니다(2026-2031년) 사이에 CAGR 1.56%로 확대한다고 추정되고 있습니다.
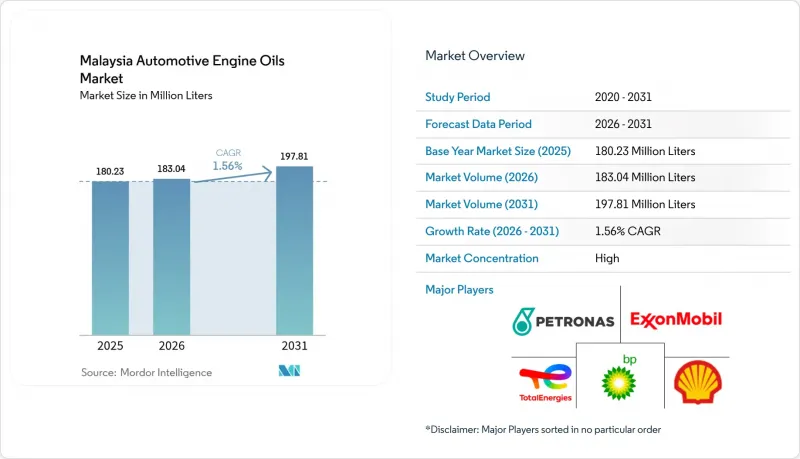
본 보고서는 제품 유형(승용차용 엔진오일(PCMO), 대형 차량용 엔진오일(HDMO), 이륜차용 엔진오일(MCO)) 및 기유(광물유, 합성유, 반합성유, 바이오베이스)별로 분류되어 있습니다. 시장 전망은 판매량(리터) 단위로 표시됩니다.
말레이시아 자동차 엔진오일 시장 동향 및 분석
라스트 마일 배송용 차량의 급속한 증가
온라인 소매 거래량이 증가함에 따라 택배 업체와 음식 배달 사업자들은 이륜차 보유 대수를 지속적으로 확대하고 있으며, Pos Malaysia만 해도 2024년에 1,092대의 전기 오토바이를 추가했지만, 여전히 훨씬 더 많은 내연기관 차량을 운영하고 있습니다. 충전 인프라 부족과 높은 초기 비용으로 인해 전환이 지연되고 있어, 2025년 한 해 동안 전기 오토바이 보급률은 1% 미만에 머물고 있으며, 그 결과 광물유와 점점 늘어나는 합성 MCO 등급 제품이 정비 공장에 계속 공급되고 있습니다. 차량 관리자들은 정비 주기를 6,000-8,000km로 연장하여 가동 중지 시간을 줄이는 한편, 주행 시간이 긴 라이더에게 보상을 제공하는 인센티브 제도와 연계하기 위해 합성 10W-40 또는 5W-40 블렌드 오일을 지정하고 있습니다. 이러한 운영상의 경제성 덕분에 전기 배송 오토바이의 부상에도 불구하고 프리미엄 등급의 채택이 유지되고 있으며, 말레이시아 자동차 엔진오일 시장에서 판매량과 매출의 점진적인 증가를 뒷받침하고 있습니다.
라이드셰어 플랫폼 차량의 급증과 대규모 서비스 제휴
Grab을 비롯한 각 라이드셰어 플랫폼 기업들은 예약 건수가 두 자릿수 성장을 기록하고 있으며, Grab의 말레이시아 법인은 2023년에 6억 7,300만 말레이시아 링깃의 매출을 올렸습니다. 이는 표준화된 정비를 받는 리스 차량 및 자사 소유 차량을 뒷받침하는 것입니다. 사업자들은 브랜드 윤활유 체인과의 대량 구매 계약을 활용하여, OEM의 API SP 또는 ILSAC GF-6A 규격을 충족하는 5W-30 합성유의 최소 구매량을 보장하고 있습니다. 1만 km 간격이라는 예측 가능한 정비 주기가 반복 수요를 확보하는 한편, 플랫폼의 데이터 분석을 통해 운전자에게 오일 교환 시기를 알리기 때문에 주요 브랜드의 고객 이탈률은 낮게 유지되고 있습니다. 그 결과, 도시 지역에서는 합성 PCMO의 보급률이 급속히 높아지고 있으며, 이는 말레이시아 자동차 엔진오일 시장의 가치 확대를 뒷받침하고 있습니다.
공유 모빌리티의 통합으로 인해 자가용의 주행 거리가 감소
카셰어링이나 구독 모델이 언론의 주목을 받고 있지만, 쿠알라룸푸르의 차량 밀도는 불과 244 km²의 면적에 70만 대를 넘고 있으며, 이는 뿌리 깊은 자가용 소유 문화와 리터당 2링깃의 보조금이 포함된 휘발유 가격을 반영한 것입니다. 사업자들은 주차 공간 부족과 감가상각 위험으로 어려움을 겪고 있으며, 공유용 차량 증가율은 등록 차량 총수에 비해 한 자릿수 초반에 그치고 있습니다. 그렇지만 공유 이용으로의 전환이 진행됨에 따라 오일 교환 빈도는 감소하고 있으며, 이는 말레이시아 자동차 엔진오일 시장의 연평균 성장률(CAGR) 예측치를 0.08포인트 낮추는 요인이 되고 있습니다.
부문 분석
2025년에도 오토바이용 엔진오일은 여전히 말레이시아 자동차 엔진오일 시장 점유율의 58.92%를 차지하고 있으며, 이는 말레이시아의 ‘2명당 오토바이 1대’라는 비율과 대규모 택배 기사층을 반영한 것입니다. 현재 PETRONAS Sprinta, Motul 300V, Gulf Syntrac이 퍼포먼스 마케팅의 주축을 이루고 있는 반면, Pos Malaysia 및 GrabFood와의 대규모 차량 계약이 대량 판매 SKU의 기반을 뒷받침하고 있습니다. 승용차용 엔진오일은 규모는 작지만, 토요타, 페로두아, 혼다가 합성 오일 서비스 패키지를 확충함에 따라 1.28%라는 가장 높은 연평균 성장률(CAGR)로 성장하고 있으며, 2022년 이후 0W-20 및 5W-30의 점유율은 3배로 확대되었습니다. Sime-UMW의 통합된 판매망을 통해 윤활유와 서비스를 결합한 프로모션이 가능해졌으며, 가격에 민감한 B부문 해치백 소유자들 사이에서 합성 승용차용 엔진오일(PCMO)의 채택이 가속화되어 말레이시아 자동차 엔진오일 시장 규모를 확대되고 있습니다.
헤비듀티용 엔진오일은 성장률 면에서는 뒤처지고 있지만, 팜유 물류, 건설, 국경을 넘는 장거리 운송 분야에서 여전히 필수적인 존재입니다. 카스트롤 ‘VECTON’ CK-4 및 페트로나스‘우라니아’ CI-4+는 B20 바이오디젤 연료 사용 시 산화 안정성을 입증했으며, 합 센 및 티온 남과의 차량 함대 시험에서 오일 교환 주기를 80,000-120,000km로 연장함으로써 사용자들의 지지를 얻고 있습니다. 향후 도입될 유로 6 규격 및 그 이상의 바이오디젤 혼합 연료는 FA-4 등급에 대한 수요 창출로 이어질 것이며, 2027년 이후에도 대형차용 합성 엔진오일의 추가적인 시장 확대가 예상됩니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
제8장 CEO가 직면하는 중요 전략적 과제
JHS 26.08.28According to Mordor Intelligence, the Malaysia automotive engine oils market size was valued at 180.23 million liters in 2025 and estimated to grow from 183.04 million liters in 2026 to reach 197.81 million liters by 2031, at a CAGR of 1.56% during the forecast period (2026-2031).
This report is Segmented by Product Type (Passenger Car Motor Oil (PCMO), Heavy Duty Motor Oil (HDMO), Motorcycle Engine Oil (MCO)), by Base Stock (Mineral, Synthetic, Semi-Synthetic, Bio-Based). The Market Forecasts are Provided in Terms of Volume (Liters).
Malaysia Automotive Engine Oils Market Trends and Insights
Rapid growth of last-mile delivery fleets
Courier and food-delivery operators continue to enlarge two-wheeler pools as online retail volume grows, and Pos Malaysia alone added 1,092 electric bikes in 2024 while still running a far larger internal-combustion roster. Electric penetration remains below 1% through 2025 as charging gaps and high upfront costs slow migration, so mineral and increasingly synthetic MCO grades keep flowing into workshops. Fleet managers specify synthetic 10W-40 or 5W-40 blends to extend service to 6,000-8,000 km, reducing downtime and aligning with rider incentive schemes that reward higher on-road hours. These operating economics sustain premium-grade uptake despite the rise of electric delivery bikes, supporting incremental volume and value for the Malaysia automotive engine oils market.
Surge in ride-hailing platform vehicles and bulk-service tie-ups
Grab and other e-hailing platforms report double-digit booking growth, and Grab's Malaysian arm booked MYR 673 million revenue in 2023, underpinning a fleet of leased and owned vehicles that undergo standardized servicing. Operators use bulk agreements with branded lubricant chains, guaranteeing minimum volumes for 5W-30 synthetics that meet OEM API SP or ILSAC GF-6A specs. Predictable maintenance cycles at 10,000 km intervals secure repeat demand, while platform data analytics alert drivers to oil-change milestones, keeping churn low for preferred brands. As a result, synthetic PCMO penetration rises faster in urban centers, reinforcing value growth for the Malaysia automotive engine oils market.
Shared-mobility consolidation reducing private-car kilometres
Car-sharing and subscription models gain media attention, yet Kuala Lumpur's vehicle density exceeds 700,000 units across just 244 km2, reflecting entrenched ownership culture and subsidized petrol at MYR 2 per liter. Operators struggle with parking shortages and depreciation risk, limiting shared-fleet growth to low-single-digit percentages of total registered cars. Even so, any incremental shift toward pooled usage compresses oil-change frequency, nibbling 0.08 percentage points off the Malaysia automotive engine oils market CAGR forecast.
Other drivers and restraints analyzed in the detailed report include:
- Tightening CO2 / Euro 6-equivalent emission norms driving premium synthetics
- Motorcycle enthusiast culture boosting high-performance oils
- Grey-market lubricants eroding branded volumes
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Motorcycle Engine Oil still commanded 58.92% of the Malaysia automotive engine oils market share in 2025, a reflection of Malaysia's 1-bike-per-2-persons ratio and a large courier workforce. PETRONAS Sprinta, Motul 300V, and Gulf Syntrac now headline performance marketing, while bulk fleet contracts with Pos Malaysia and GrabFood anchor high-volume SKUs. Passenger Car Motor Oil, though smaller, grows at the swiftest 1.28% CAGR as Toyota, Perodua, and Honda broaden synthetic service packages, trebling 0W-20 and 5W-30 share since 2022. Sime-UMW's unified distributor footprint allows bundled lubricant-plus-service promotions that accelerate synthetic PCMO adoption among cost-sensitive B-segment hatchback owners, bolstering value for the Malaysia automotive engine oils market size.
Heavy Duty Motor Oil trails in growth terms but remains vital for palm-oil logistics, construction, and cross-border haulage. Castrol VECTON CK-4 and PETRONAS Urania CI-4+ command loyalty by proving oxidation stability with B20 biodiesel, extending drains to 80,000-120,000 km in fleet trials with Hap Seng and Tiong Nam. Upcoming Euro 6 and higher biodiesel blends create an opening for FA-4 grades, positioning heavy-duty synthetics for renewed expansion beyond 2027.
Complete Report Scope:
- By Product Type
- Passenger Car Motor Oil (PCMO)
- 0W-XX
- 5W-XX
- 10W-XX
- 15W-XX
- Monogrades
- Other Grades
- Heavy Duty Motor Oil (HDMO)
- 0W-XX
- 5W-XX
- 10W-XX
- 15W-XX
- Monogrades
- Other Grades
- Motorcycle Engine Oil (MCO)
- 0W-XX
- 5W-XX
- 10W-XX
- 15W-XX
- Monogrades
- Other Grades
- Passenger Car Motor Oil (PCMO)
- By Base Stock
- Mineral
- Synthetic
- Semi-Synthetic
- Bio-Based
List of Companies Covered in this Report:
- Bardahl
- BP plc
- Chevron Corporation
- ENEOS Corporation
- Exxon Mobil Corporation
- FUCHS
- Gulf Oil International Ltd
- Idemitsu Kosan Co Ltd
- Liqui Moly
- Motul
- PETRONAS Lubricants
- Repsol
- Saudi Arabian Oil Co.
- Shell plc
- Sinopec Lubricant (Singapore) Pte Ltd
- SK Inc.
- TotalEnergies SE
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid growth of last-mile delivery fleets
- 4.2.2 Surge in ride-hailing platform vehicles and bulk-service tie-ups
- 4.2.3 Tightening CO2 / Euro 6-equivalent emission norms driving premium synthetics
- 4.2.4 OEM-mandated extended-drain intervals raising per-fill value
- 4.2.5 Motorcycle enthusiast culture boosting high-performance oils
- 4.3 Market Restraints
- 4.3.1 Shared-mobility consolidation reducing private-car kilometres
- 4.3.2 Grey-import lubricants eroding branded volumes
- 4.3.3 Rising drain-intervals lowering service frequency
- 4.4 Value Chain and Distribution Channel Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Industry Rivalry
- 4.6 Regulatory Framework
- 4.7 Automotive Industry Trends
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Product Type
- 5.1.1 Passenger Car Motor Oil (PCMO)
- 5.1.1.1 0W-XX
- 5.1.1.2 5W-XX
- 5.1.1.3 10W-XX
- 5.1.1.4 15W-XX
- 5.1.1.5 Monogrades
- 5.1.1.6 Other Grades
- 5.1.2 Heavy Duty Motor Oil (HDMO)
- 5.1.2.1 0W-XX
- 5.1.2.2 5W-XX
- 5.1.2.3 10W-XX
- 5.1.2.4 15W-XX
- 5.1.2.5 Monogrades
- 5.1.2.6 Other Grades
- 5.1.3 Motorcycle Engine Oil (MCO)
- 5.1.3.1 0W-XX
- 5.1.3.2 5W-XX
- 5.1.3.3 10W-XX
- 5.1.3.4 15W-XX
- 5.1.3.5 Monogrades
- 5.1.3.6 Other Grades
- 5.1.1 Passenger Car Motor Oil (PCMO)
- 5.2 By Base Stock
- 5.2.1 Mineral
- 5.2.2 Synthetic
- 5.2.3 Semi-Synthetic
- 5.2.4 Bio-Based
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)**/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Production Capacity, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Bardahl
- 6.4.2 BP plc
- 6.4.3 Chevron Corporation
- 6.4.4 ENEOS Corporation
- 6.4.5 Exxon Mobil Corporation
- 6.4.6 FUCHS
- 6.4.7 Gulf Oil International Ltd
- 6.4.8 Idemitsu Kosan Co Ltd
- 6.4.9 Liqui Moly
- 6.4.10 Motul
- 6.4.11 PETRONAS Lubricants
- 6.4.12 Repsol
- 6.4.13 Saudi Arabian Oil Co.
- 6.4.14 Shell plc
- 6.4.15 Sinopec Lubricant (Singapore) Pte Ltd
- 6.4.16 SK Inc.
- 6.4.17 TotalEnergies SE
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment


